GE HealthCare’s agreement to acquire SOFIE Biosciences for $945 million in cash is not just another healthcare M&A headline. It is a direct move into one of precision medicine’s most stubborn operational constraints: getting a PET radiopharmaceutical dose from production to a patient before too much of it decays.
The deal, announced Oct. 5 and expected to close in the first half of 2027 pending regulatory approvals, would bring SOFIE’s 15 U.S. contract-manufacturing sites, 21 cyclotrons and a theranostics-focused development and manufacturing site into GE HealthCare’s Pharmaceutical Diagnostics segment. It also gives GE U.S. rights to SOFIE’s Phase III PET tracer FAPI-74, complementing rights it already holds outside the United States.
That makes the real question larger than whether radiopharmaceuticals are a growth market. The sharper question is whether GE is mainly buying a promising asset base — or control over a supply chain whose economics are dictated by radioactive decay, local production density and trusted access for competitors.
What GE is really buying
The most important asset here may be neither a molecule nor a customer list. It is network density.
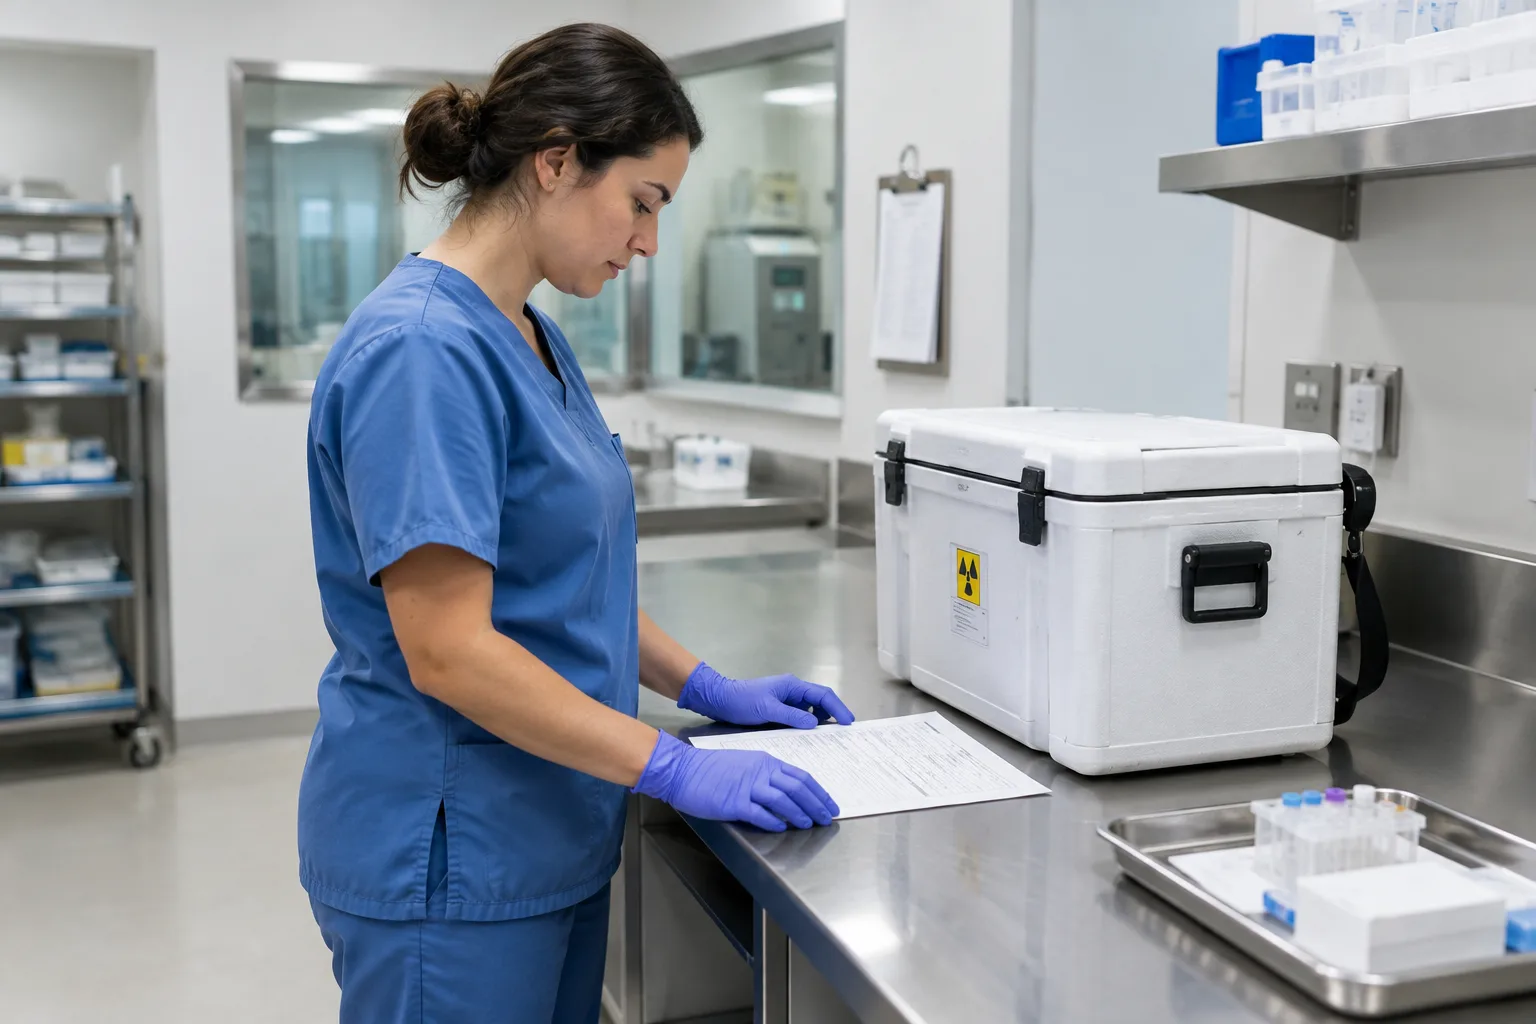
GE describes the transaction as a “final mile” move, and that framing matters. F-18 labeled PET radiopharmaceuticals have a roughly 110-minute half-life. According to FDA guidance on PET drugs, these products are typically administered within minutes to a few hours after preparation, which gives them unusual storage, shipping and handling requirements. In practice, that means a PET dose is not simply invented in a lab and sold nationally like conventional medicine. It has to be manufactured regionally, quality-released quickly, routed carefully and delivered on a tight schedule.
That is why SOFIE’s footprint is strategically valuable. A network of 15 U.S. CMO sites and 21 cyclotrons could, in principle, provide more local production options, more scheduling flexibility and more backup paths when something goes wrong — a failed batch, a transport delay, a staffing problem, weather. GE also says SOFIE already manufactures its Flyrcado F-18 injection product, so the companies are not starting from zero operationally.
The acquisition also adds a pipeline position. FAPI-74 targets fibroblast activation protein and is in Phase III development as a diagnostic PET tracer with possible oncology and theranostic uses. That is meaningful, but it is not the same thing as buying an approved blockbuster. The product’s clinical results, regulatory path, labeling, reimbursement and launch timing remain unresolved. What GE is acquiring on that front is optionality, not certainty.
The third asset is adjacency. GE already sells imaging systems, imaging agents and digital workflow tools. More reliable local radiopharmaceutical supply can make it easier for hospitals and imaging centers to schedule PET procedures. If those procedures become easier to schedule and support, that can reinforce demand for the scanners and software that sit downstream.
Why the final mile matters more than the headline multiple
Healthcare investors often look first for revenue synergies or a near-term earnings story. GE has described the transaction in growth and accretion terms, but the operational logic is more interesting.
PET adoption does not depend only on whether a tracer works clinically or wins regulatory approval. It also depends on whether a hospital can count on getting a usable dose when the patient, scanner, staff and interpreting physician are all lined up. Short-lived radionuclides make ordinary national distribution economics less useful. Distance is not abstract; it eats into the product.
That helps explain why analysts, as reported by MedTech Dive, viewed added manufacturing and distribution capacity as one possible way to reduce bottlenecks in radiopharmaceutical adoption. The problem is not simply demand creation. It is orchestration.
Still, bigger is not automatically better. The public announcement does not say how SOFIE’s 15 sites are distributed, how much redundancy exists between them, how fully utilized they are or how much faster they make delivery. More nodes and cyclotrons should improve resilience only if quality systems, release timing, transport routes, staffing and hospital scheduling all work together. A large network on paper can still have local blind spots in practice.
The neutrality test starts now
The strategic upside comes with a governance problem that will matter immediately to customers and regulators.
SOFIE is not just a manufacturer for GE products. It is a contract manufacturer for multiple radiopharmaceutical companies. GE says SOFIE will continue to operate as an independent manufacturing partner for existing customers, including other radiopharmaceutical providers, after closing. Reuters independently reported that point along with the price, U.S. FAPI-74 rights and expected timing.
That promise is central to the deal’s credibility. Once GE owns the network, it will control capacity that rival providers may depend on at the same time that it owns competing products and a richer tracer pipeline. The risks are not theoretical: scarce slots, pricing, production priority, commercial information handling and investment decisions can all influence whether a “neutral” CMO remains truly neutral.
None of that means anti-competitive harm is inevitable, and there is not enough public information to say whether regulators will require remedies. But the burden of proof will shift from strategy slides to operating behavior. If non-GE customers keep access, service levels and confidence, the network becomes more valuable to everyone using it. If they see subtle steering toward GE’s own portfolio, the acquisition could tighten supply for the market even while expanding GE’s footprint.
What will show whether the strategy is working
The cleanest way to judge this deal is not by the headline price or by management forecasts. It is by what changes on the ground after closing.
Hospitals and imaging centers should watch whether delivery radii expand, on-time dose rates improve and backup options become more credible when a batch fails or transport slips. Radiopharmaceutical companies that use SOFIE will care about capacity allocation, pricing discipline, quality performance and whether information firewalls hold.
Investors should watch customer retention, any disclosed expansion of the site network, treatment of non-GE products and whether GE can translate supply reliability into higher procedure volumes or stronger pull-through for imaging equipment and workflow software. And for FAPI-74, the decisive evidence will be Phase III data and subsequent regulatory progress, not the fact that rights changed hands.
GE is buying growth potential, but the more consequential prize is control of a supply chain that runs on a 110-minute clock. If the company can use ownership to make PET supply more reliable while preserving SOFIE’s value as a neutral manufacturing partner, this will look like smart vertical adjacency. If it cannot, the deal will show how hard it is to own the last mile in radiopharmaceuticals without distorting it.
 By
 By
 By

 By


 By