
Private SpaceTech investment hit a record $20.8 billion in the third quarter, according to Seraphim’s Q3 2026 SpaceTech Investment Tracker, with 216 deals completed in the period. That was nearly triple Q2’s $7.4 billion and more than double the previous peak. The number matters because it points to something larger than a burst of startup enthusiasm: capital is pouring into launch, manufacturing, satellite networks and other physical systems that businesses and governments increasingly treat as strategic infrastructure.
The harder question is whether that money signals a durable build-out or a quarter flattered by one giant financing and a launch bottleneck. For now, the answer is somewhere in between. Q3 was clearly exceptional, and Seraphim itself expects moderation. But even after removing Blue Origin’s $10 billion round, the quarter still set a record at $10.8 billion. That suggests real breadth in investor demand. What it does not prove is that funded companies can convert capital into flight cadence, delivered satellites, paying customers and profitable service on the timelines implied by the funding headlines.
A record quarter with a large asterisk
Blue Origin was the biggest deal in the quarter by far, and its financing heavily shapes the top-line number. That makes it important to separate the headline from the underlying pattern. The quarter’s 216 deals, up from 140 in Q2, show more activity across the market, not just one mega-round. Seraphim’s trailing-twelve-month figures also point to sustained volume: $40.1 billion invested across 666 deals through Q3.
Still, the deal-size math is a useful reality check. The average Q3 deal was $137 million, while the median was only $9.8 million. In practical terms, that means a typical company was raising something much smaller than the headline average suggests. The average was pulled sharply upward by Blue Origin and a handful of large rounds, including $1.37 billion for Hadrian, $1 billion for Stoke Space and $500 million for K2 Space.
That gap matters for readers trying to gauge market health. A soaring average can make the whole sector look flush. The median says many companies are still operating on financing more consistent with long, capital-intensive development programs than with businesses already throwing off dependable cash flow.
It also matters because Seraphim’s tracker is an investment dataset, not a sector income statement. It captures arm’s-length third-party private capital across financing types, but it does not provide a company-by-company picture of backlog, launch success, profitability, insurance exposure or how much of a round is staged against future milestones. Funding is evidence that investors are willing to underwrite the build-out. It is not evidence that the build-out is complete.
Capital is chasing bottlenecks
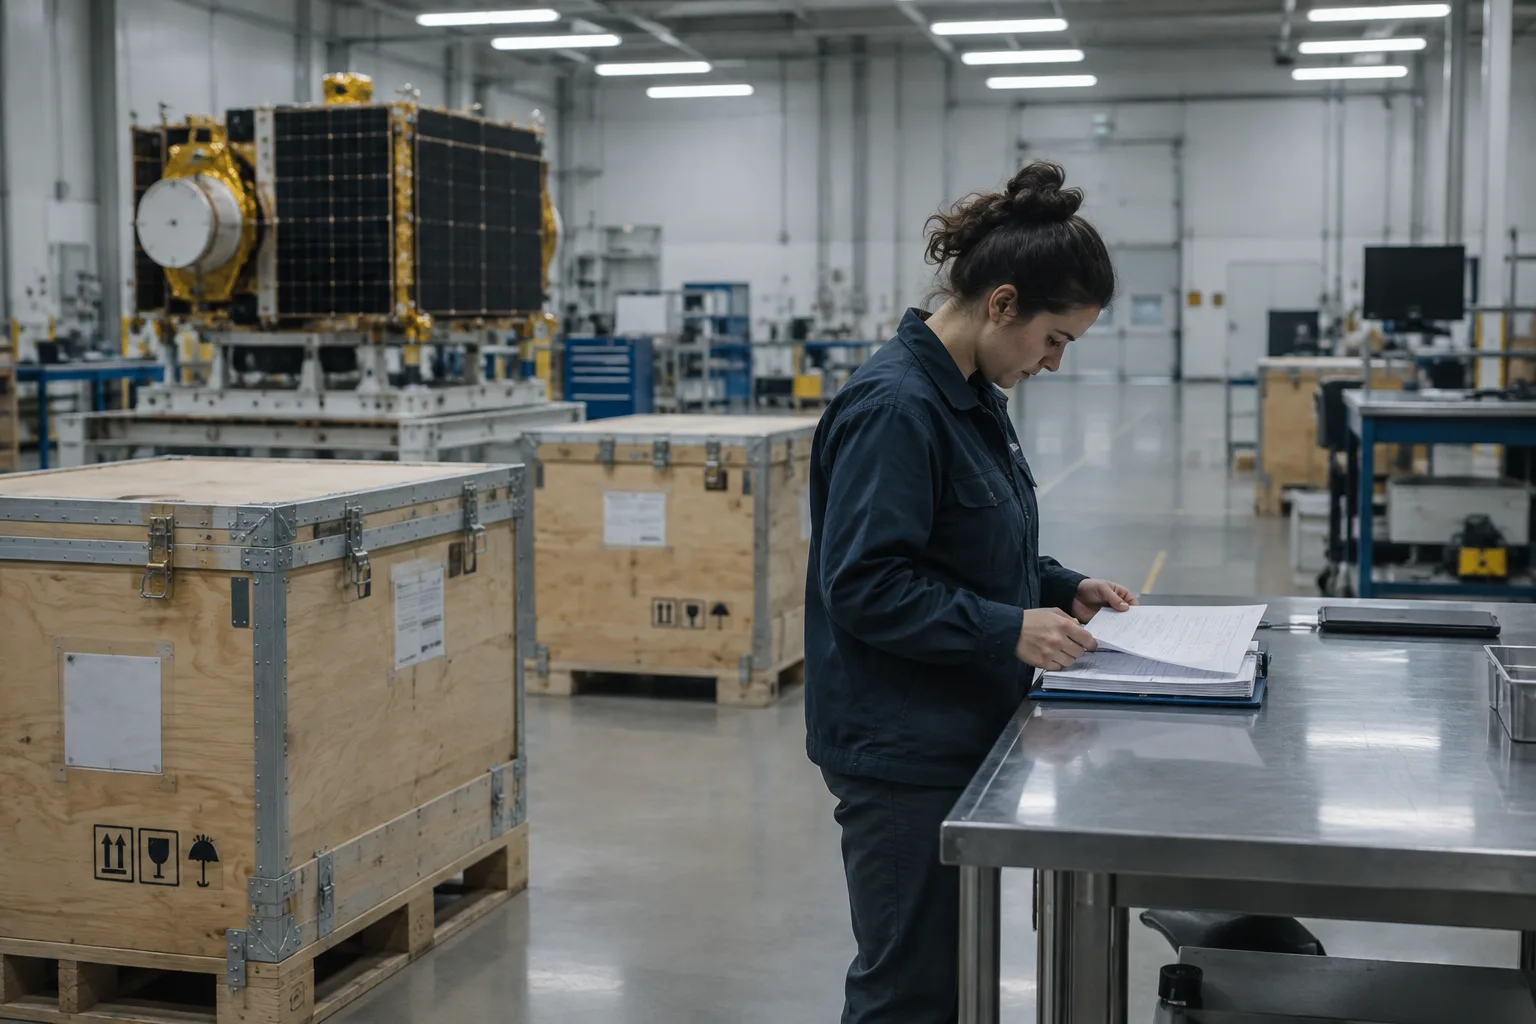
Where the money went helps explain what investors think the problem is. Launch and broader space-access businesses drew $16.4 billion across 120 deals in Q3, dwarfing the roughly $4 billion raised by satellite communications, Earth observation and other space services. This was an infrastructure quarter.
That distinction is important. Space markets can look software-like from the outside because the end products include connectivity, imagery and data. Underneath, they depend on rockets, satellites, factories, components, testing, licensing, insurance, spectrum rights and ground systems. All of those are slow-moving, hardware-heavy constraints. They absorb capital long before they produce recurring revenue.
Recent launch-market reporting helps explain why investors may be willing to fund alternatives so aggressively. MarketWatch reported that SpaceX stopped accepting ride-share reservations beyond late 2028 while it concentrates resources on Starlink and Starship. That is not proof that every new launcher now has a clear commercial path, and it does not show how many missions are delayed or what prices will do. It does show why capital would gravitate toward companies promising more access, more manufacturing throughput or more flexibility in orbit.
Scarcity can be attractive to investors for two very different reasons. In the optimistic version, a capacity squeeze reveals durable unmet demand and opens room for new providers. In the harsher version, the same squeeze creates cost overruns, schedule slippage, insurance complications and customer frustration that funded companies struggle to overcome. Both can be true at once.
That is why the record is best read as a sign of strategic urgency, not commercial maturity. North America accounted for about 70% of year-to-date global funding, according to Reuters, while China reached a quarterly high of $3.3 billion across 49 deals. Those numbers suggest the market is being shaped not only by private demand, but by geopolitical competition and government priorities. Defense and civil-agency demand can provide anchor customers for launch and satellite programs. They can also slow revenue recognition when procurement cycles, appropriations or policy shifts intervene.
The checklist that matters now
For founders and investors, the immediate temptation is to treat Q3 as a verdict on which business models have won. It is too early for that. Many listed space companies remain loss-making, a reminder that raising money and building a self-sustaining operation are separate achievements.
A more useful way to read the quarter is as a screening tool. The companies most likely to justify the new flood of capital are the ones that can answer a set of operational questions clearly and soon: How often can they actually fly? How many satellites have they delivered? Do they have signed commercial contracts as well as government work? Are customers coming back for repeat orders? Can they manufacture at volume without introducing quality problems? Do they have redundancy in launch access, components and ground infrastructure? Are insurance costs manageable? Are unit economics improving as production scales?
Those questions matter beyond the investor class. Launch customers need schedule certainty. Satellite operators need confidence that funded suppliers can get hardware into orbit. Insurers need data on reliability and delays. Suppliers want to know whether this quarter’s big commitments translate into steady orders or merely bigger inventories. Businesses that rely on space-based connectivity or Earth data care less about fundraising records than about whether service becomes more available, resilient and affordable.
The clearest reading of Q3 is that space is attracting infrastructure-scale capital because demand from commercial markets and government programs looks real enough to finance more capacity. But the record should not be confused with proof that capacity is already there. In that sense, the quarter looks less like a finished boom than a race to relieve choke points. Some of that money will create durable platforms. Some of it may end up waiting for launch slots, contracts or technical milestones. The next few quarters will matter less for how much capital is announced than for how much of this newly funded capacity actually comes online.
 By
 By
 By

 By

 By