Nscale has done something that makes AI infrastructure feel less like a startup story and more like a capital-markets one. On Sept. 25, the UK-based AI cloud company said it raised $3.36 billion in pre-IPO financing through convertible loan notes, with Third Point leading and NVIDIA, Apollo- and Citadel-managed funds, the Abu Dhabi Investment Council, 8090 Industries and other institutions participating.
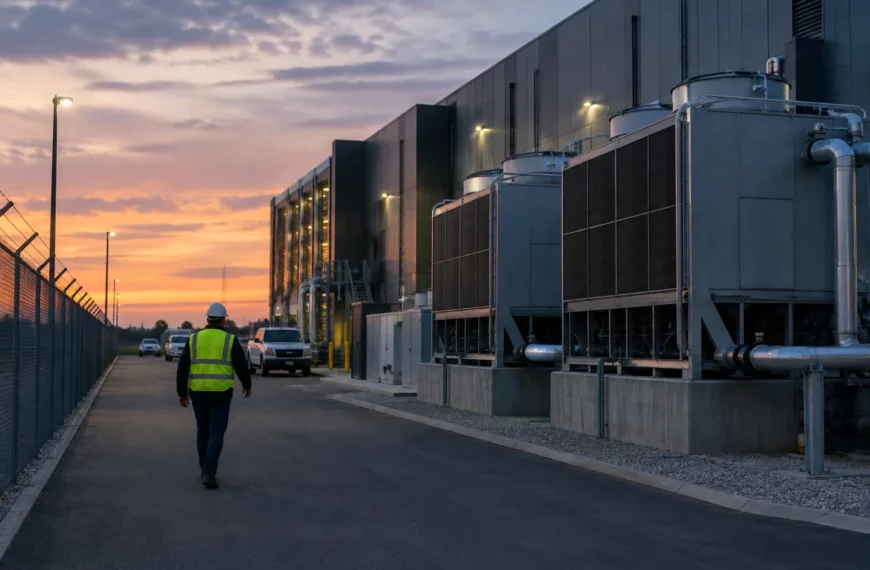
The size matters. So does the structure. Nscale filed publicly for a New York Stock Exchange listing just a week earlier, but its IPO is still unpriced and not yet effective. The convertible raise gives the company cash now—$2.36 billion at closing, plus a further $1 billion commitment from NVIDIA expected in mid-November—without forcing an immediate public valuation. For a business that has to secure power, build data centers, install liquid cooling and buy GPUs before customers can consume compute, that timing advantage is the point.
The question investors and customers should actually be asking is not whether demand for AI compute exists. It plainly does. The question is whether this financing turns Nscale into a durable infrastructure business, or mainly buys time before the harder test: converting very large contract commitments into operating capacity, recognized revenue and reliable service.
What the financing solves
A convertible note is a practical instrument for a company in Nscale’s position. The capital arrives before the IPO, while the final equity economics are deferred until a public listing. Nscale said the proceeds will help accelerate its vertically integrated AI infrastructure strategy across power, liquid-cooled data centers and GPU clusters.
That is exactly where the money is needed. AI infrastructure providers do not scale like software companies. Land, power interconnection, buildings, networking equipment, cooling systems, operations teams and hardware all have to be financed before revenue fully shows up. In that sense, the new raise is a meaningful vote that large investors are willing to fund the physical layer of AI.
But the financing also comes with important blank spaces. Nscale did not disclose the conversion price, any discount, the interest rate, maturity, covenants or what happens if the IPO takes longer than expected or does not happen on the hoped-for timetable. That leaves public-market investors unable to judge the eventual dilution or how much protection noteholders secured against execution risk.
NVIDIA’s participation cuts both ways as well. It strengthens confidence that a crucial hardware supplier is aligned with the company’s expansion, and Nscale said NVIDIA’s securities will be non-voting shares upon conversion. But it also underlines concentration: NVIDIA is not just a supplier in this market, but now part of the capital stack.
The $103 billion headline needs a delivery discount
Nscale’s financing announcement points to more than $103 billion in total contracted value. That is the number that grabs attention, but it is not revenue, and it is not a measure of capacity already online.
The sharper picture comes from the company’s S-1 filing. For the six months ended June 30, 2026, Nscale reported $140.6 million in revenue, up from $10.4 million a year earlier. That growth is real. So is the loss profile: net loss widened to $1.02 billion from $368.9 million in the comparable period.
Its operating footprint is also much smaller than the contract headline suggests. As of Aug. 31, the filing described roughly 25,000 active GPUs and 461,000 active or contracted GPUs across five active and twelve contracted sites, representing about 1.37 gigawatts of active and contracted capacity. In other words, most of the opportunity still depends on projects that must be financed, permitted, constructed and equipped.
That is why the company’s own split between active and contracted business matters more than the top-line contract figure. The S-1 identifies about $2.6 billion of active contract value versus roughly $103.4 billion of active plus contracted total contract value. The gap between those numbers is the execution challenge.
Customer concentration is the real underwriting issue
Nscale’s business may be selling compute, but the financing case increasingly looks like project underwriting. The crucial question is how firm the demand is once construction delays, power availability and customer rights are taken into account.
According to TechCrunch’s review of the filing, Microsoft agreements represent about $43.8 billion through 2033 and Anthropic agreements about $44.6 billion—together around 85% of stated contract value. That concentration is large enough that it changes how the story should be read. These are not dozens of small customers smoothing risk across a broad portfolio. They are a few giant counterparties driving the economics.
And not all contracted value is equally secure. The Anthropic agreement, as described in the filing and highlighted by TechCrunch, depends on Nscale obtaining financing and meeting demanding delivery milestones, with rights to cancel or walk away if those conditions are not met. Those commitments may still prove valuable, but they do not function like revenue already earned or cash already collected.
That distinction matters for everyone around the company: prospective IPO investors trying to price execution risk, enterprise and AI-lab customers deciding whether capacity will arrive on time, utilities and local governments planning around campus buildouts, and lenders or developers considering whether long-term compute contracts are financeable collateral.
What to watch before the IPO story becomes an operating story
The bullish case is straightforward. Nscale now has billions in fresh capital, institutional backers with real balance sheets, revenue that is growing quickly and customer contracts that point to strong demand for AI infrastructure. In a market where power and compute remain constrained, that combination can be powerful.
The caution is just as straightforward. A large financing round validates access to capital; it does not validate returns on capital. Nscale still has to translate contract demand into permitted sites, installed GPUs, service uptime and recurring revenue at margins that justify the buildout. The company’s current active base—25,000 GPUs against 461,000 active or contracted—shows how much of the plan remains ahead rather than behind it.
That makes the most useful scorecard surprisingly concrete. Watch whether contracted sites become active sites. Watch whether active GPUs scale in line with commitments. Watch whether customer concentration eases or deepens. Watch whether the company can grow revenue without losses expanding at the same pace. And watch whether Nscale’s dependence on NVIDIA looks like strategic alignment or a sign that supplier concentration is being mistaken for independent market validation.
Nscale’s raise is big enough to move AI infrastructure out of niche financing and into the mainstream business conversation. But it does not settle the central question. It sharpens it. The next phase is not about whether capital can be assembled around AI demand. It is about whether that capital can build enough real, operating capacity to turn a contract pipeline into an enduring business.
 By
 By
 By
 By



 By
 By