EliseAI has raised $350 million at a $4 billion valuation, a big private-market bet that AI will create durable value not by answering open-ended prompts but by taking over repetitive, regulated work inside apartment operations and healthcare administration. The round, announced Sept. 29, matters because it suggests investors are rewarding distribution, workflow coverage and revenue in essential services over the more familiar story of model demos and chatbot novelty.
The question behind the headline is simpler than the financing mechanics: is EliseAI showing that vertical AI can genuinely improve the economics of housing and healthcare, or are investors paying ahead of proof that those gains reach renters, patients and workers rather than just owners, providers and the vendor itself?
Why this round stands out
EliseAI said the financing was led by Andreessen Horowitz and Bessemer Venture Partners, with participation from Ontario Teachers’ Pension Plan, Sapphire Ventures and Navitas Capital. According to Fortune, the round consisted entirely of primary capital and nearly doubled the company’s valuation from the $2.2 billion attached to its $250 million Series E about 13 months earlier.
That matters for two reasons. First, primary capital means the money is going into the company rather than mainly to existing shareholders cashing out. Second, the valuation implies that investors believe EliseAI has moved beyond experiment status. The company says it now generates more than $200 million in annual recurring revenue, a figure that has not been publicly audited, and reaches 6.5 million housing units. In its own Sept. 29 announcement, EliseAI described that footprint as one in five U.S. multifamily apartments; a syndicated company release described it as one in six. Either way, the claimed reach is large enough to make the company more than a niche tool.
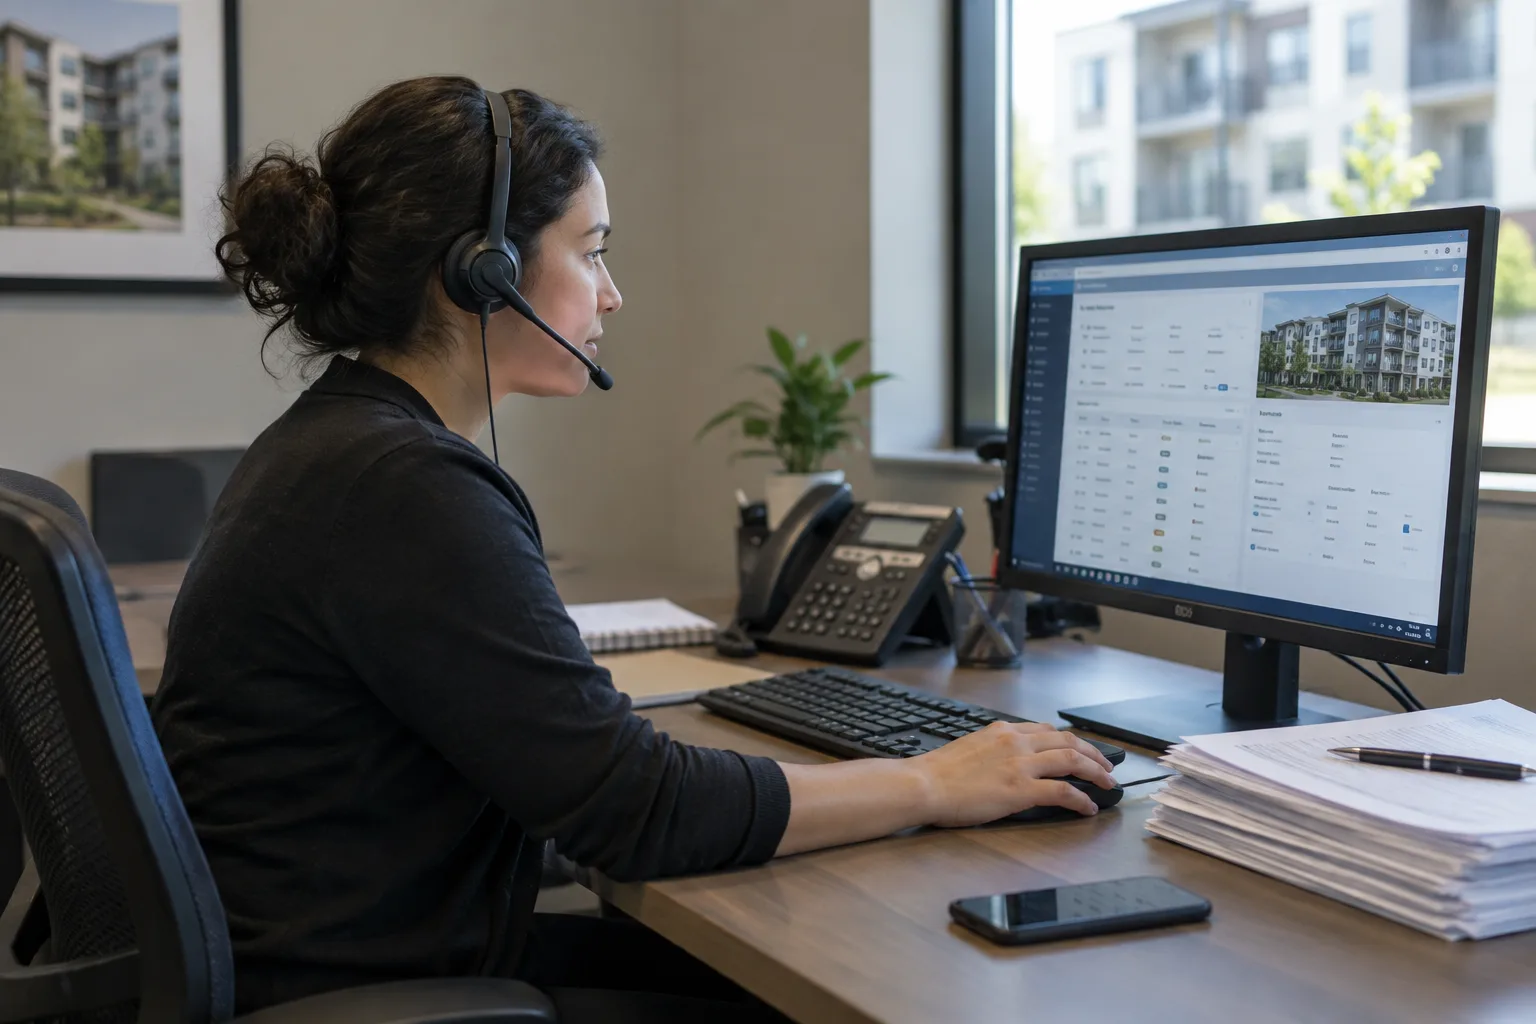
EliseAI says it will use the new money to expand product development and grow engineering, deployment and sales across North America, including a second engineering hub in San Francisco alongside its New York headquarters. That hiring plan fits the business it has built. EliseAI was founded around operational workflows in property management and healthcare administration, not as a general-purpose assistant. Its products handle leasing, resident communications, scheduling and other repetitive service and back-office processes, and the company says it is pushing further into day-to-day operations.
The case investors are buying
The strongest argument for EliseAI is not that it has a flashier model than everyone else. It is that narrow, industry-specific automation can be harder to replace once it is embedded in the messier parts of real work: routing inquiries, handling follow-ups, scheduling, intake, document collection and escalating exceptions to humans.
That is the core vertical-AI pitch. In sectors like housing and healthcare, the value sits less in raw model performance than in integrations, workflow rules, operational data and the ability to expand inside an account after landing an initial use case. A landlord or healthcare operator is not buying a chatbot for entertainment. They are buying fewer missed calls, faster responses, better coverage after hours, more consistent follow-up and, ideally, a measurable lift in revenue or operating efficiency.
EliseAI is presenting exactly that story. In its Sept. 29 announcement, the company said that across the units it serves, occupancy is two percentage points higher, residents are seven percentage points more likely to renew and net operating income rises by as much as 20%. If those gains hold up, they would help explain the valuation. A vendor that can reliably improve occupancy and renewals at scale becomes part of the economic engine of a property, not just another software line item.
The same logic applies in healthcare administration, where missed messages, scheduling bottlenecks and intake delays can be expensive and frustrating. Here too, the attraction is not novelty. It is throughput.
What the valuation does not settle
The problem is that the most important operating claims are still claims. The public record does not spell out the methodology behind EliseAI’s occupancy, renewal or NOI figures, and it does not show the sample size, time period, comparison group or statistical controls. A stronger property cohort, local market conditions, pricing changes or broader service improvements could help produce the same results. That does not make EliseAI wrong. It does mean the round should be read as a market signal, not as independent proof.
The same caution applies to reach and revenue. More than $200 million in ARR and millions of covered units indicate real distribution, but they do not answer the questions enterprise buyers should care about next: retention, gross margin, customer concentration, implementation cost, contract length, churn and how much of the business comes from housing versus healthcare. None of that was disclosed in the announcement.
There is also the human side of automation. Property management and healthcare administration are full of repetitive tasks, but they also involve fair-housing obligations, personal and medical information, and situations where a scripted response is not enough. A system that handles high volumes of messages can improve speed while still creating new risks if its classifications, routing or communications are wrong. At scale, a small error can propagate across many properties or care sites before anyone catches it.
That is why the real diligence questions are operational, not theatrical. How much of the workflow is automated? How often are exceptions kicked to a human? How fast can staff audit or reverse a bad routing decision? What controls govern data access? In housing, how are automated communications tested for fair-housing compliance, and what is the appeal path for a resident who believes the system got something wrong? In healthcare, where the public materials are thinner on compliance details, what is reviewed by people, what is logged, and who is accountable for high-impact administrative decisions?
Who is likely to benefit
Investors clearly see a company with traction in hard-to-serve industries. Fortune reported this was the fourth financing involving a16z and Bessemer since 2023, a sign that existing backers believe the company’s distribution advantage is strengthening. EliseAI also says its revenue has doubled year over year for five consecutive years, which, if sustained, would help explain why fresh capital arrived at a sharply higher price.
But the next phase of the story is less about whether AI can answer leasing or scheduling inquiries and more about who captures the productivity it creates. Owners and providers may gain higher occupancy or lower administrative cost. The vendor may gain pricing power if it becomes deeply embedded. Frontline staff may be pushed into higher-value exception handling, or see hours reduced. Renters and patients may get faster responses, or they may find it harder to reach a person when the automated path fails.
That is the lasting significance of EliseAI’s raise. It shows that private capital is ready to treat vertical AI in essential services as infrastructure. What it does not yet show, at least in the public record, is how consistently the gains are measured, how widely they are shared, or how safely the system behaves when the workflow stops being routine. For landlords, healthcare operators and enterprise buyers, the useful scorecard now is not just ARR and valuation, but retention, workflow coverage, escalation rates, implementation time, compliance controls and independently measured outcomes.
 By
 By
 By
 By
 By