
EigenQ and Silicon Valley Acquisition Corp. said September 18 they have secured approximately $45 million of committed financing through a convertible note, with roughly half funded upfront and the remainder expected when their previously announced business combination closes. That matters less as a capital-markets event than as a commercialization test: if post-quantum security is becoming ordinary enterprise infrastructure, companies in the category should be able to turn standards-driven urgency into deployments, channel revenue, and durable cash flow.
The real question is not whether quantum risk exists. It is whether EigenQ’s new money finances near-term, paid post-quantum-security rollouts, or mainly buys time for a still-unproven SPAC story to reach the public market.
According to the companies’ PR Newswire release, about $22.5 million is funded upfront. The rest is expected at completion of the proposed EigenQ-SVAQ merger, which would take EigenQ public under EIGQ if approvals and other closing conditions are met. That means the headline number is meaningful, but not the same as $45 million of cash in hand today.
What the financing changes right now
For an early-stage infrastructure company, the upfront tranche is not trivial. EigenQ says it will use the proceeds to commercialize its quantum-safe security portfolio, expand OEM and channel delivery, continue R&D across quantum security, communications, networking, and sensing, and support working capital. In practical terms, that can fund the expensive middle of enterprise selling: product integration, partner enablement, deployment support, and the payroll needed to survive slow procurement cycles.
The second tranche changes the picture. Because that capital is tied to the merger closing, the note functions partly as bridge financing. It gives EigenQ room to operate now while still depending on a larger corporate event later. That is an important distinction for customers, who care about vendor durability, and for investors, who care about how much of the financing is certain, how conversion terms work, and what dilution may follow. The public materials do not answer those questions in detail.
SVAQ and EigenQ announced their business combination on June 17 with an estimated pro forma enterprise value of approximately $3 billion and an expected fourth-quarter 2026 closing. But that valuation is part of the deal announcement, not a market-tested result, and the September financing does not complete the merger. The most useful reading is that EigenQ has improved its odds of making it to the next milestone, not that it has already arrived.
Why the market timing is real
There is a serious demand-side story here. NIST finalized FIPS 203, 204, and 205 in August 2024, establishing key-establishment and digital-signature standards designed to resist future quantum-computer attacks. Its guidance tells organizations to inventory vulnerable cryptography and begin migration.
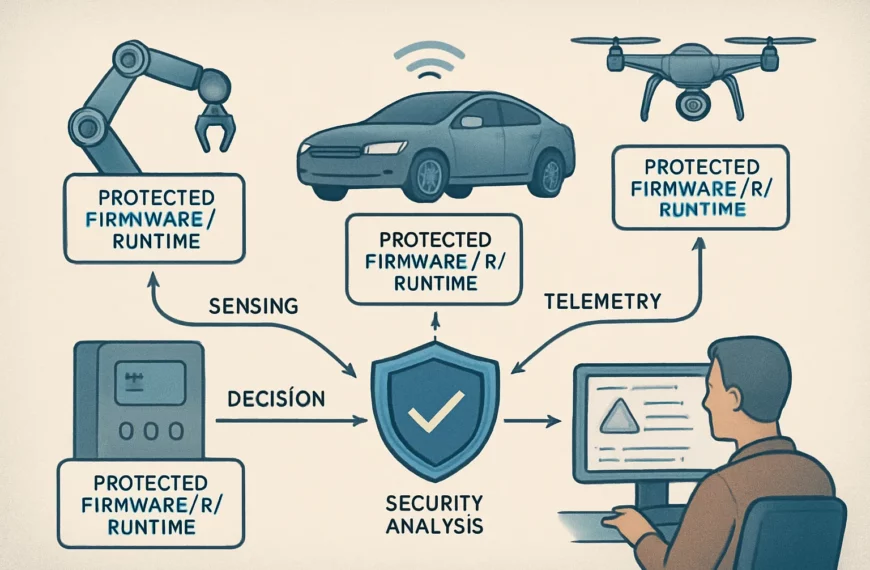
That creates genuine budget pressure across ordinary computing environments: servers, edge devices, networking gear, embedded systems, and long-lived infrastructure that cannot wait for a distant hardware refresh. Post-quantum cryptography is a migration problem, not proof that someone has built a useful quantum computer. Companies that can make migration cheaper, safer, and easier to manage may find a real market.
That is why EigenQ’s positioning is commercially legible even without a headline-grabbing quantum-computing breakthrough. The release cites collaborations involving TD SYNNEX and AMD, WNC, and HPE and Intel ecosystem integrations. If those relationships produce live products and supported deployments, they could matter more than flashy research claims. Distribution, OEM design wins, and interoperability inside existing enterprise stacks are how security infrastructure usually becomes repeatable.
But the release stops short of proving that step has happened. It does not provide customer revenue, contract values, deployment counts, or independent product-validation results. It does not show whether the integrations are shipping in volume, whether procurement teams have approved them, or whether customers are renewing. In a standards-driven migration cycle, those details separate a promising architecture from a repeatable business.
The numbers that keep this grounded
EigenQ’s historical financial base remains small. In EigenQ’s 2025 Form C-AR, the company reported $6,194.47 in revenue, $1,370,590.68 in expenses, a net loss of $1,444,376.21, and operating cash flow of negative $1,424,948.68 for the year ended December 31, 2025. Those figures are backward-looking, not a forecast for 2026, but they frame the gap between commercialization ambition and documented scale.
That gap does not invalidate the financing. Many deep-tech companies spend well ahead of revenue while trying to land design wins and enterprise credibility. It does mean the burden of proof is still high. A partner list is not the same thing as booked business. A planned SPAC listing is not the same thing as public-market validation. A NIST migration mandate does not tell buyers which vendor will win.
So what would change the story from speculative to durable? Buyers and investors should look for a short list of proof points: implemented support for the NIST standards; validation or certification that matters in procurement; crypto-agility across servers and edge devices; live OEM products rather than announced integrations; paying customers rather than ecosystem affiliations; recurring software or attestation revenue layered on top of hardware; and, if the merger closes, enough post-transaction cash runway to support customer commitments.
Until then, the September note reads as both opportunity and warning. Opportunity, because the migration wave is real and the upfront capital can help EigenQ meet it. Warning, because the company still has to show that recognizable partners, claimed integrations, and merger-linked financing translate into the one thing enterprise infrastructure businesses eventually need most: repeatable, paid adoption.
 By
 By
 By


 By


 By