Microsoft is urging the Trump administration to back away from an expected restriction on Chinese-made optical transceivers used in AI data centers, according to Reuters. The fight matters because transceivers are not a side component. They are the optical links that connect servers, switches, and routers over fiber, and without enough qualified modules, expensive AI chips can sit installed but not operating as a usable cluster.
That turns the reader’s real question into a practical one: can the United States tighten security around AI data-center networking without creating a shortage that delays new capacity? On the facts now public, that looks less like a yes-or-no debate than a policy-design problem. A narrowly scoped, future-facing rule could reduce exposure to a sensitive supply chain while giving operators time to adapt. A broad or fast-moving restriction could shift the AI bottleneck from chips and power to optics.
Reuters reported that Microsoft and other companies or trade groups met White House Office of Science and Technology Policy and National Security Council officials in September to discuss supply-chain challenges. Microsoft declined comment, and the White House and FCC did not comment. The report, citing three people familiar with the discussions, says the FCC is considering limits on new Chinese optical-transceiver models, potentially around a 3.2-terabits-per-second threshold, though no rule has been published or adopted.
The new choke point in AI buildouts
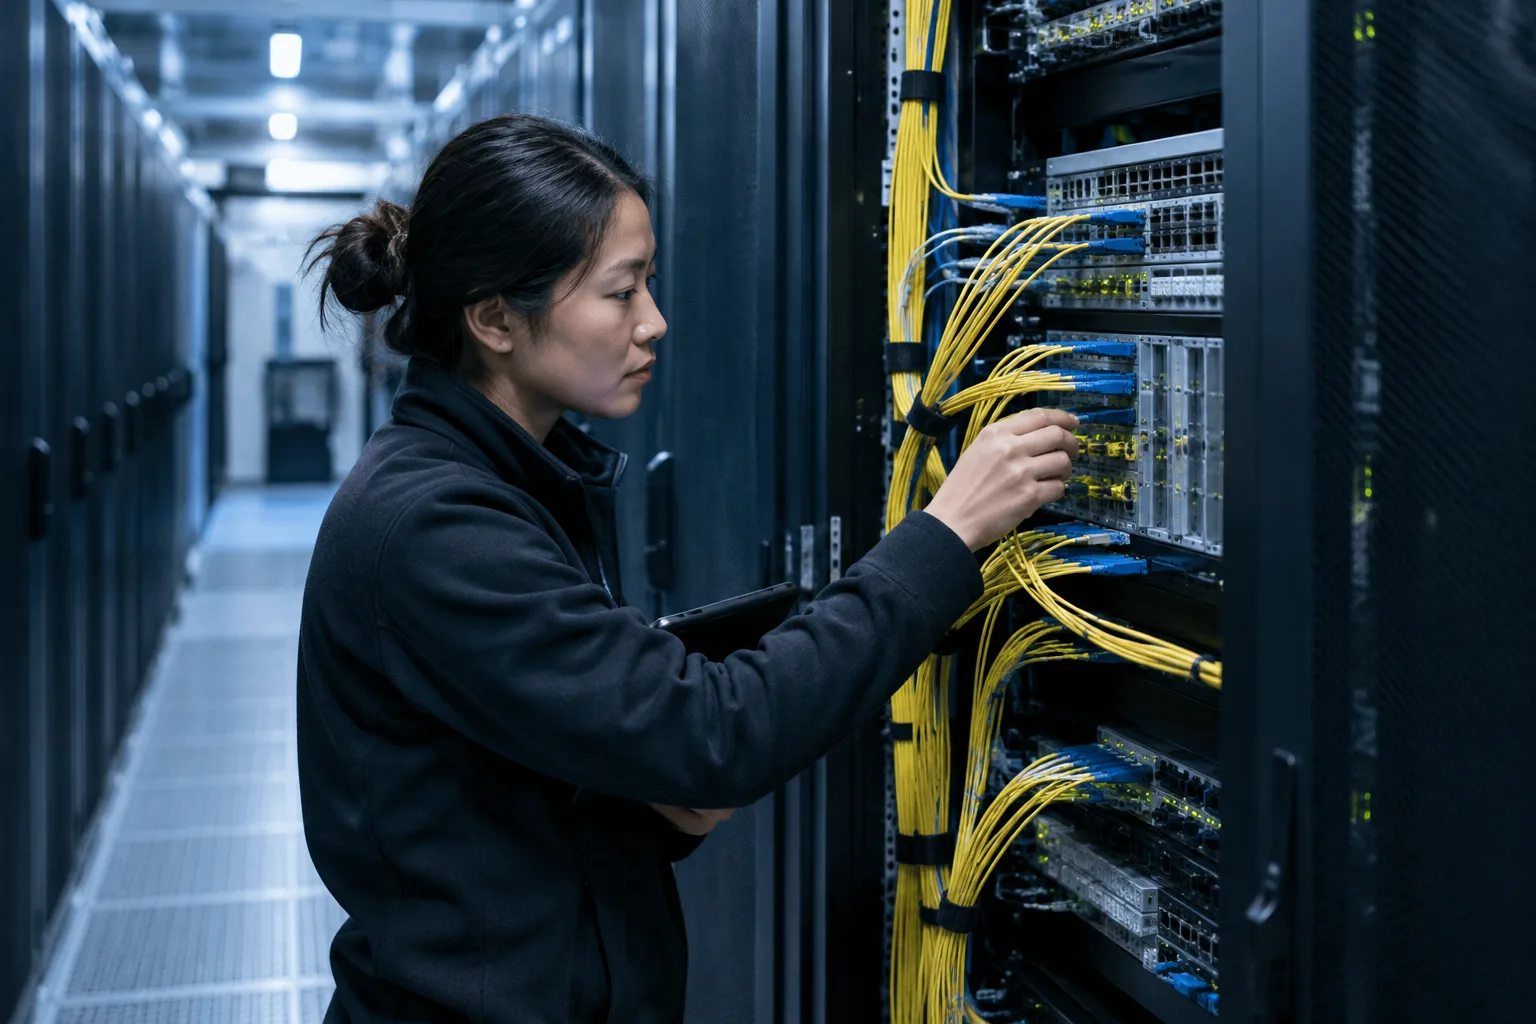
The strategic point is simple: AI infrastructure now depends on more than GPUs. It depends on the network that lets thousands of accelerators behave like one machine. Optical transceivers perform the electrical-to-light conversion that carries that traffic across fiber between racks and across the facility. In a large AI cluster, the module count can run into the millions, which makes a small-looking component systemically important.
That is why this proposal reaches beyond telecom policy. Reuters says Microsoft has 35 U.S. data centers under construction and 134 planned, citing Cleanview. Any operator building at that scale has to think about whether optics are available, whether they have passed qualification, and whether mixed generations from different suppliers can work together. If the answer is no, the problem is not theoretical. It becomes delayed commissioning, stranded accelerator inventory, and slower delivery of cloud capacity to customers.
The supply picture helps explain the industry anxiety. Counterpoint data cited by Reuters puts China at roughly two-thirds of the global optical-transceiver market. Reuters also cited Innolight, also known as Zhongji Innolight, at about 27% of the global data-center transceiver market. U.S. competitors including Coherent and Lumentum make rival products, but sources cited in the reporting said they do not have the same scale.
That does not mean a restriction is unworkable. It means the timing and scope will decide whether the policy behaves like a security control or a supply shock.
The policy question is design, not just intent
The security rationale is easy to state even if the public record remains thin on specifics. Reuters reported in August that the FCC was drafting a measure to bar imports of new Chinese optical transceivers over concerns about data theft, malware, and service disruption. Optical modules sit deep inside critical infrastructure, so Washington is treating them as more than commodity parts.
But the open questions are what make this story consequential. There is still no public FCC text, no final product list, no implementation date, no exemption process, and no clarity on whether any action would cover imports only, use in U.S. facilities, federal procurement, or already installed equipment. It is also unclear whether existing inventory would be grandfathered or how suppliers would prove origin and security.
Those details matter more than the headline phrase “ban.” A rule focused on future, very-high-speed generations could give domestic and allied suppliers time to scale while avoiding immediate disruption to equipment already designed into projects. Reuters cited a Morgan Stanley note from October discussing a possible 3.2 Tbps threshold and analyst expectations that production might not ramp until 2028, with widespread installation in 2029. Those are not government dates, but they point to the difference between a targeted transition and a near-term cutoff.
A broader restriction would land differently. Replacing a supplier inside a data-center network is not like swapping office hardware. Operators may need redesign work, new validation, firmware review, spare-parts planning, and fresh interoperability testing across switches, servers, and optical layers. The cost is not only the price of the module. It is the schedule risk and engineering effort that come with changing a foundational component late in the build.
There is also a narrower policy track that should not be confused with the FCC proposal. Bipartisan lawmakers introduced a September bill that would bar the federal government from equipping sensitive systems with Chinese-made transceivers. That would be a more limited intervention than an import rule affecting the broader commercial market.
What cloud and data-center operators should do now
For operators, the immediate task is not to predict the final FCC rule. It is to expose their own dependencies before Washington does it for them. That means mapping which transceiver generations are used or planned, where those products were made, what firmware and update controls exist, and how much inventory is already on order. It also means identifying qualified U.S. or allied substitutes, estimating replacement lead times, and modeling whether a facility can operate with mixed generations or mixed suppliers.
That checklist matters just as much to cloud customers as to the builders themselves. A delayed data center can turn into delayed capacity allocations, higher prices, or slower deployment of AI services. Investors in optics suppliers, colocation operators, and contractors tied to new campuses all have exposure to the same policy variable: not whether optics are important, but whether a security rule is precise enough to avoid becoming the next buildout bottleneck.
The lobbying campaign reported by Reuters should be read in that light. Microsoft does not need to prove that all restrictions are wrong to make its case. It only needs to show that a blunt restriction could leave a large share of planned AI infrastructure waiting on one class of parts. The FCC and lawmakers, meanwhile, do not need evidence of a publicly documented compromise inside an American AI data center to argue that the supply chain is too sensitive to ignore.
The likely test for policymakers is whether they can separate those two truths. If the rule is narrow, phased, and clear about what happens to existing inventory and future generations, the United States may be able to reduce network risk without freezing capacity. If it is broad, immediate, or vague, the next shortage in AI may arrive not at the chip foundry or the power substation, but at the fiber port between them.
 By
 By
 By
 By


 By


 By