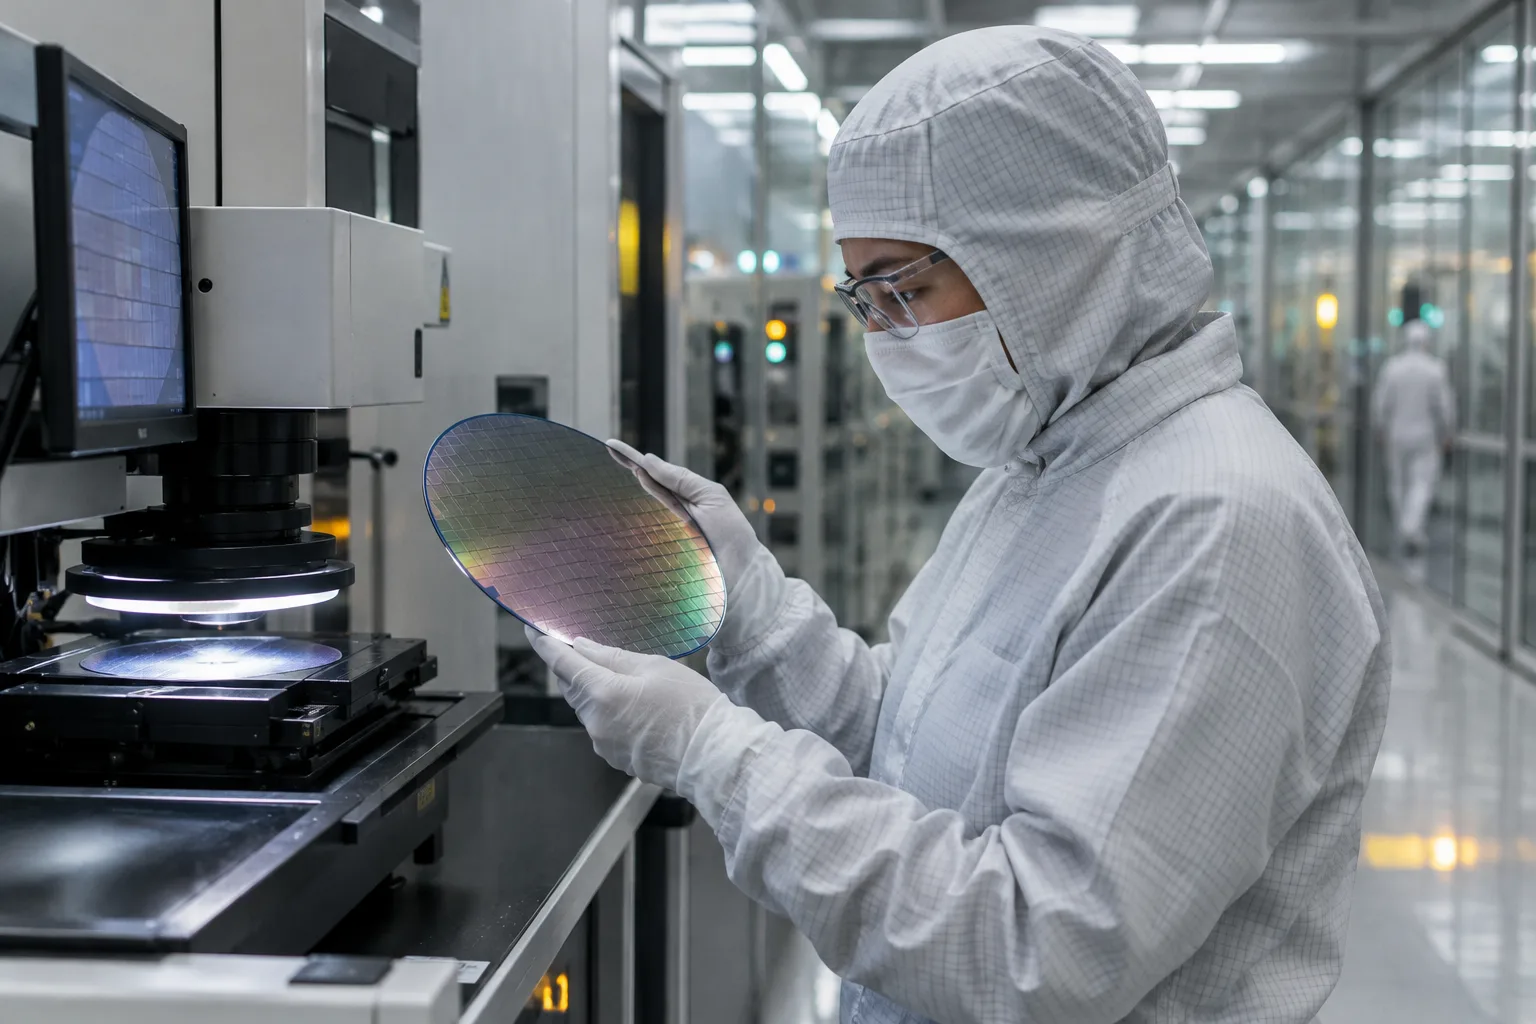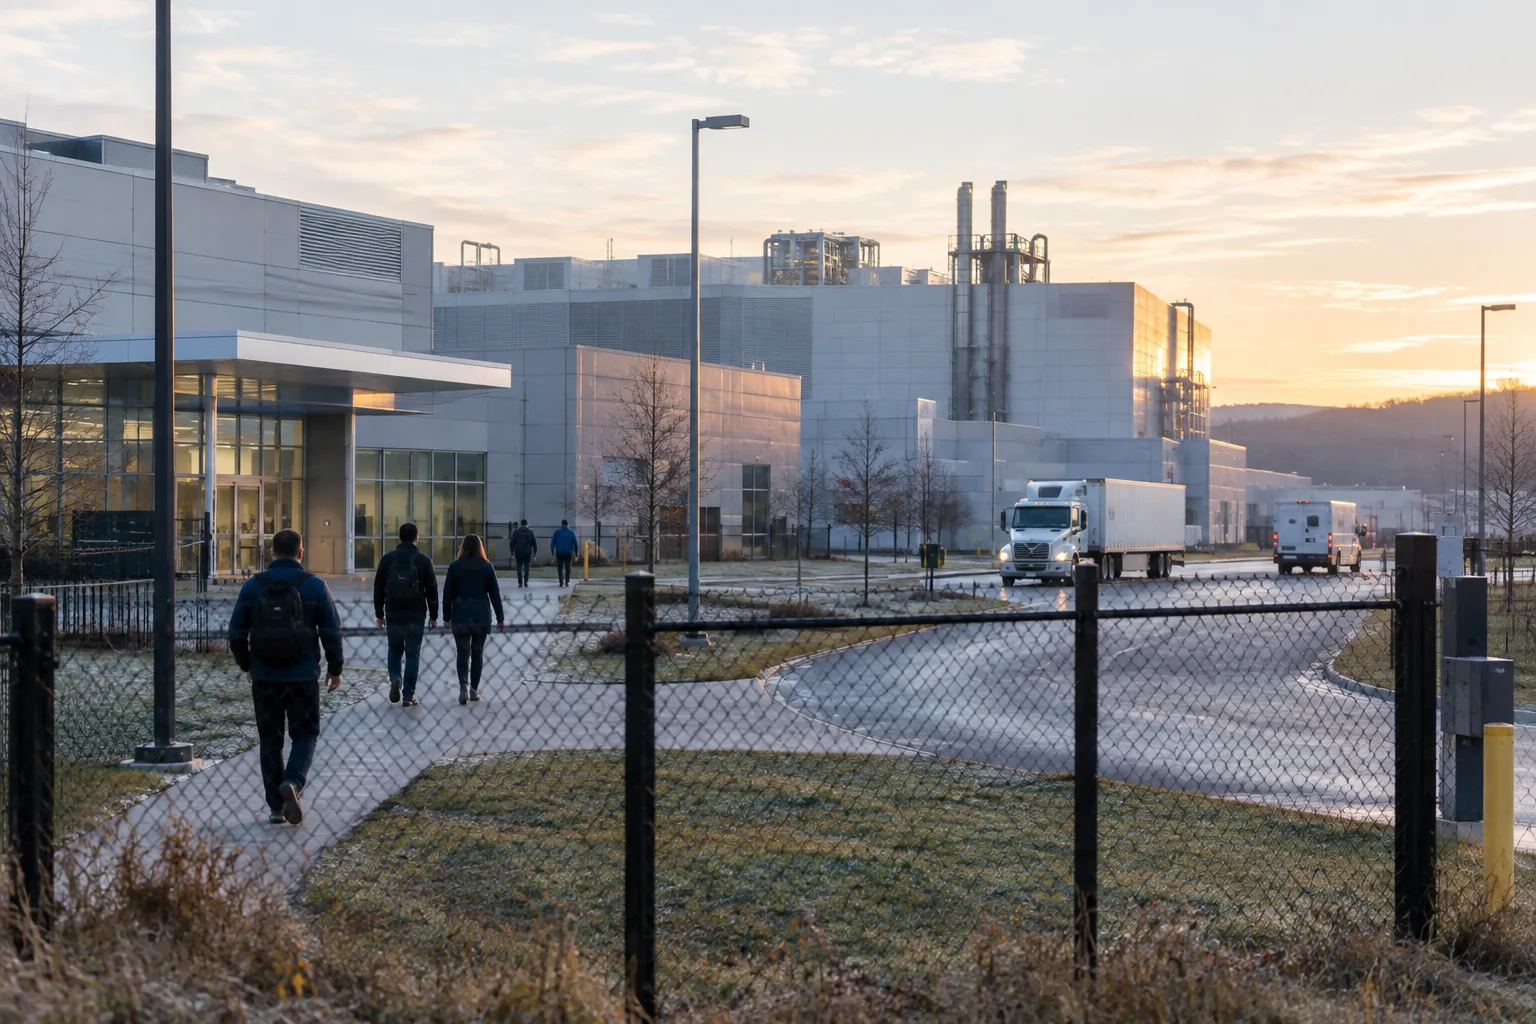

GlobalFoundries and Taiwan Semiconductor Manufacturing Co. have signed a $2 billion, five-year agreement to establish a U.S.-based supply of silicon interposers for TSMC’s CoWoS advanced-packaging ecosystem, with production expected to begin ramping in the first half of 2028 at GF’s Malta, New York, site. The deal matters because the interposer is the layer that helps bind AI processors to stacks of high-bandwidth memory, and advanced packaging has become one of the industry’s hardest constraints.
The useful question is not whether the announcement sounds strategic. It is whether a new U.S. interposer source will materially loosen the packaging bottleneck for AI systems, or mostly create a future domestic component source whose value still depends on capacity, yield, qualification, downstream assembly and customer demand. For now, the answer is mixed: this is a meaningful shift in supply-chain design, but not yet proof of more shipped AI systems.
Why this layer matters
TSMC describes CoWoS as a 2.5D advanced-packaging platform for high-performance computing and AI. Its CoWoS-S version uses a silicon interposer to connect system-on-chip devices and HBM stacks through dense, high-speed links, allowing separate chips to behave as one high-performance package. TSMC says CoWoS has been in volume production since 2012, with demand accelerating sharply after generative AI took off in 2022, and that it continues to expand both interposer size and packaging capacity.
That context changes how this deal should be read. For years, the semiconductor conversation centered on who could fabricate the most advanced logic die. In AI, that is no longer enough. More compute and more memory only turn into shippable product if interposers, substrates, bonding, HBM supply, assembly, test, power delivery and thermal design all scale together. A shortage in any one layer can delay a package even when the logic die itself is available. The interposer is not the whole bottleneck, but it is one of the layers that now matters.
What the agreement actually changes
In its company announcement, GlobalFoundries said it will manufacture interposers for TSMC rather than replace TSMC’s CoWoS assembly flow or customer relationships. That distinction is important. This is not a case of TSMC recreating its entire advanced-packaging stack in upstate New York. It is a production split: TSMC keeps the platform and likely the customer-facing package integration, while GF adds U.S. manufacturing capacity for a critical component at an existing site.
The companies say the planned source would be the first U.S.-based supply of silicon interposers for this CoWoS ecosystem. GF also said the Malta output can include embedded deep-trench-capacitor components, and the agreement provides a framework for additional capacity expansion if demand grows. For U.S. industrial policy, that is a practical model of resilience. It relies on specialization and partnership rather than trying to duplicate every backend step in one country or one fab.
For customers, the attraction is straightforward. A domestic interposer source could reduce exposure to a backend supply chain concentrated in Asia and may help buyers that care about U.S.-based manufacturing provenance or procurement risk. But buyers should keep the layers distinct. The announcement covers a U.S. interposer source inside a TSMC-centered packaging architecture; it does not say that HBM, final assembly, test and every other downstream step move to the U.S. The strategic gain is diversification within the existing CoWoS ecosystem, not independence from it.
The scorecard for 2028
The part that matters most now is also the part the companies have not disclosed. There is no public annual interposer capacity for Malta, no wafer-start figure, no package-unit output, no customer allocation, and no clear view of how much of the $2 billion is fixed versus demand-dependent. The headline number is the announced value of the initial five-year agreement, not a disclosed annual revenue run rate or profit figure for GF. There is also no public indication of take-or-pay terms, minimum volumes, capacity reservations or expansion milestones.
That makes it hard to judge whether this will be a major addition to AI-package supply or a strategically useful but numerically modest one. For device makers, cloud operators planning 2028 deployments, suppliers and investors, the denominator matters. A new source can be important without being large enough to change overall market tightness. Right now, the announcement establishes intent, location and timing better than it establishes scale.
Qualification is the second test. It is not public how GF’s process will be matched against TSMC’s existing interposer sources, what defect-density and reliability targets apply, how cycle times will compare, or exactly how the Malta output will fit into the rest of the CoWoS flow. The announcement also does not explain where final assembly and test will occur or how HBM supply will be coordinated. Those are not side issues. An interposer only relieves a bottleneck if memory stacks, substrates, packaging lines and test capacity are available to turn that part into a finished module.
Timing matters too. A first-half-2028 ramp is concrete enough to shape planning, but it is still more than a year away and leaves room for the usual risks around equipment installation, yield learning and customer qualification. Reuters reported that GF shares rose about 4% in premarket trading after the announcement, which shows investors see strategic value. It does not show that qualification is complete or that total AI-system output will rise.
The best way to read this deal is as the AI supply chain moving one layer deeper. It acknowledges that packaging components now deserve the same strategic attention once reserved for leading-edge logic wafers. If Malta reaches volume on schedule, qualifies cleanly inside TSMC’s CoWoS flow and feeds enough downstream assembly to matter, the agreement could become an important U.S. anchor for AI infrastructure. Until those milestones are visible, though, the deal is less a solution to packaging scarcity than a serious attempt to build optionality where the bottleneck has quietly moved.
 By
 By
 By
 By



 By