
On October 19, 2026, Tenstorrent said it closed a $1.5 billion Series E at a $6.2 billion post-money valuation, a financing large enough to matter well beyond venture-capital scorekeeping. In its announcement, the company said the money will go to volume manufacturing and global commercial expansion, including scaling its Galaxy servers, supporting open-weight large language models and video-generation workloads, and advancing AI and CPU intellectual property for customers designing their own silicon.
That makes this less a story about startup paper value than about whether an alternative AI-compute stack can become operationally real. Tenstorrent is trying to sell several things at once: RISC-V-based processors and AI chips, open-source software, deployable servers, and licensable IP. The question for buyers is straightforward: does this round move Tenstorrent from promising architecture and demonstrations to repeatable supply, support, and customer deployments?
What the round actually funds
The round was led by Trace Capital and Innovation X. Tenstorrent also listed a long roster of new and existing participants, including Fidelity Management & Research Company, Morgan Stanley, T. Rowe Price, ARK Invest, Sandisk, Virtu Financial, and XTX Markets, alongside a mix of other institutional and strategic backers. The size and composition of the syndicate suggest that investors see this as infrastructure financing, not a narrow component bet.
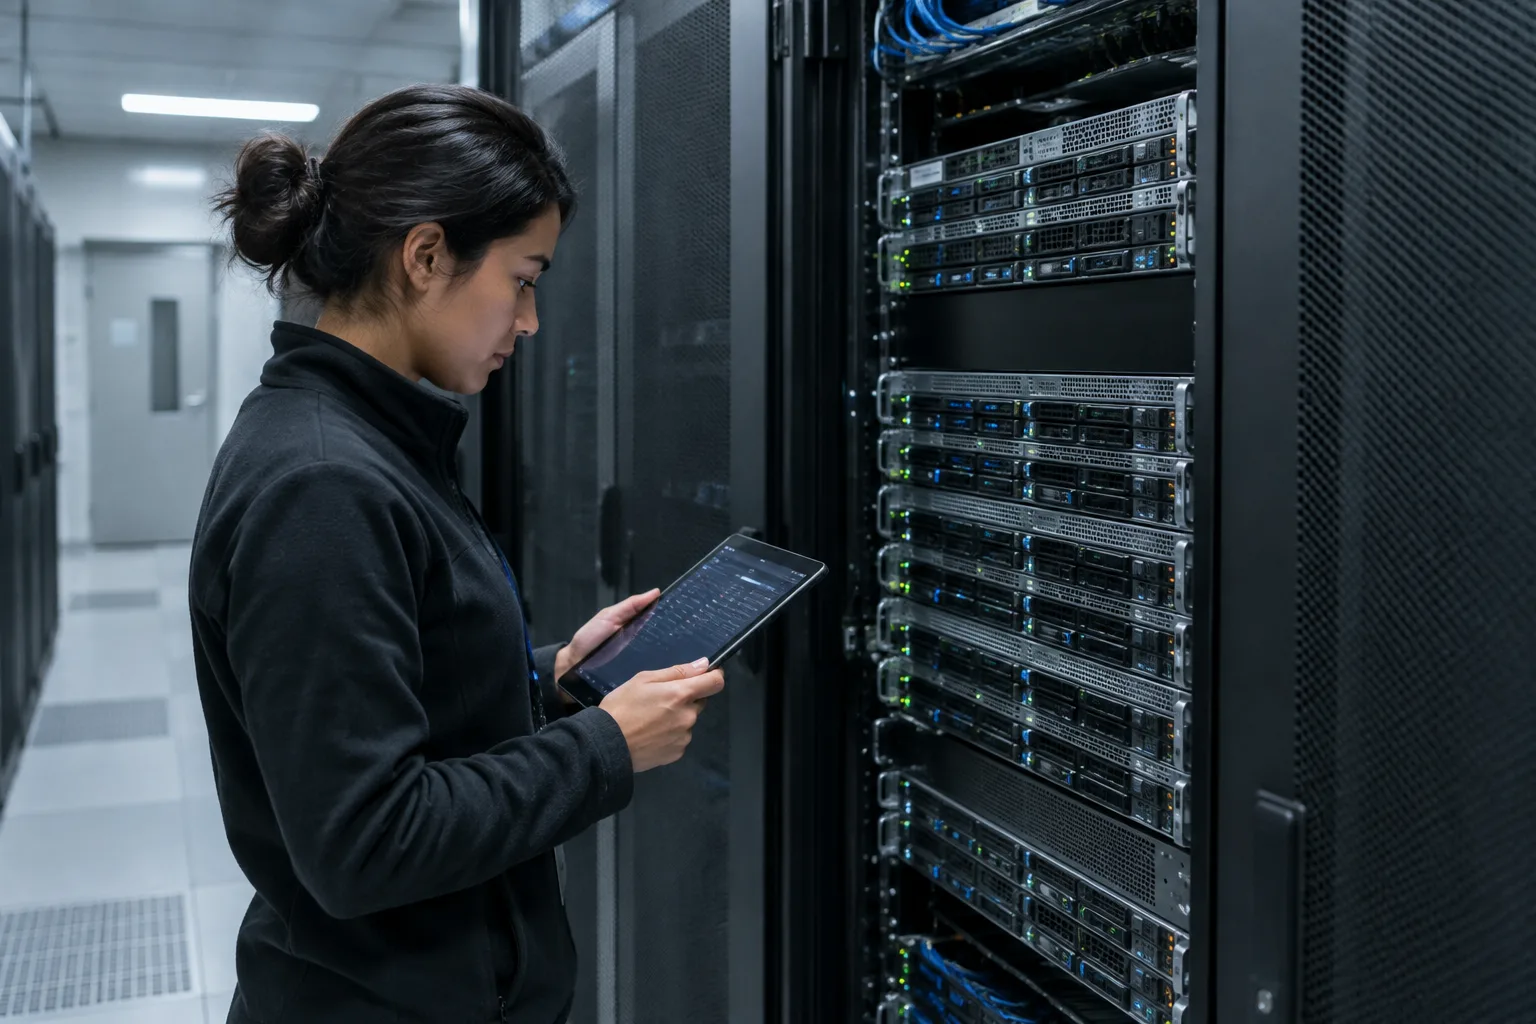
That distinction matters because AI customers do not buy an instruction set alone. They buy chips, packaging, boards, racks, networking, software tools, model support, service commitments, and predictable delivery. Tenstorrent says its stack spans a single card or workstation, racks and superclusters, and custom IP for customers building their own chips. It also says developers can run frontier models locally and enterprises can deploy models on-premise.
The money is supposed to finance that whole conversion from architecture to product. If Tenstorrent can use the capital to secure manufacturing, build and ship Galaxy systems, and support customer silicon programs, the raise could widen the market for buyers that want inference capacity without being tied entirely to a proprietary accelerator ecosystem.
Why Tenstorrent’s pitch is different
Tenstorrent’s strategy stands apart from the simpler “next Nvidia” shorthand because it is not only selling accelerator cards. Reuters described Galaxy as server systems that combine dozens of the company’s AI chips for workloads such as chatbots, coding assistants, and video generators. Reuters also noted that Tenstorrent develops chips and software using RISC-V, the open processor architecture that can reduce dependence on proprietary licensing models such as Arm’s.
That RISC-V angle is meaningful, but only in a specific way. Openness can give chip designers and sovereign-compute programs more control over their processor roadmap and licensing exposure. It does not, by itself, create a mature commercial ecosystem. Buyers still need compilers, libraries, drivers, model kernels, monitoring, security updates, trained engineers, and enough volume to make hardware economical.
Tenstorrent is also leaning into a part of the AI market that may be easier to enter than top-end training: inference. Inference workloads run after a model is trained, and customers often care about latency, energy use, throughput, memory movement, and whether they can place systems close to users or inside their own facilities. Open-weight models and on-premise deployment can make those tradeoffs more attractive for enterprises, neocloud operators, and government-backed compute programs.
TechCrunch reported that CEO Jim Keller said the company chose to remain independent and raise more capital after showing that Galaxy servers could run DeepSeek models. That helps explain investor enthusiasm. A demonstrated workload is better than a slide deck. But a demonstration still sits well short of proving broad production compatibility or attractive economics across customer environments.
What the money does not prove
The valuation has clearly jumped. Reuters reported that the new round more than doubled Tenstorrent’s valuation from the prior financing period, and said the company’s December 2024 raise brought in more than $693 million at a $2 billion pre-money valuation.
What the new money does not answer is just as important. Tenstorrent’s public materials do not disclose revenue, gross margin, backlog, cash balance, customer concentration, unit pricing, yield, or a delivery schedule for Galaxy systems. They do not say how many customer systems are already deployed, how much of the round is meant for servers versus IP and software, or which foundry, packaging, and supply arrangements will carry the company into volume production.
There is also no independently audited benchmark table in the public record comparing Tenstorrent against current Nvidia or AMD systems on representative inference workloads. “Open-weight” and “on-premise” describe customer options, not proof of lower cost, lower power use, or better performance. The same goes for software maturity: public reporting does not establish how broadly production models are supported, how much engineering work customers must do to port workloads, or what support and warranty terms they receive once systems are installed.
That is why the most useful way to read this financing is as capital for proof, not proof itself.
The next evidence that matters
For enterprise buyers, cloud operators, chip designers, and suppliers, the next phase is less about headlines and more about verification gates. First is supply: production volume, delivery dates, and whether advanced packaging, memory, networking, power delivery, and cooling can scale without becoming the real bottleneck. Second is deployment: whether customers can install Galaxy systems and run real model workloads without rebuilding their software organization around a niche stack.
Third is economics. Buyers will want end-to-end performance per dollar and per watt, not isolated chip claims. They will want to know rack-level requirements, model and framework coverage, the engineering cost of porting, and whether repeat orders or design-ins are showing up. Because Tenstorrent also licenses IP, revenue mix matters too: the company could build a durable business through customer silicon wins even if its own server volumes remain limited.
That leaves Tenstorrent in a serious but still unproven position. The company now has the capital to pursue manufacturing, systems, and licensing at a scale that few AI-chip startups can match. What it still has to show is the harder part: that an open alternative can become boring in the best possible way — installable, supportable, forecastable, and economical enough that customers choose it for production work, not just as an interesting second option.
 By
 By
 By
 By

 By