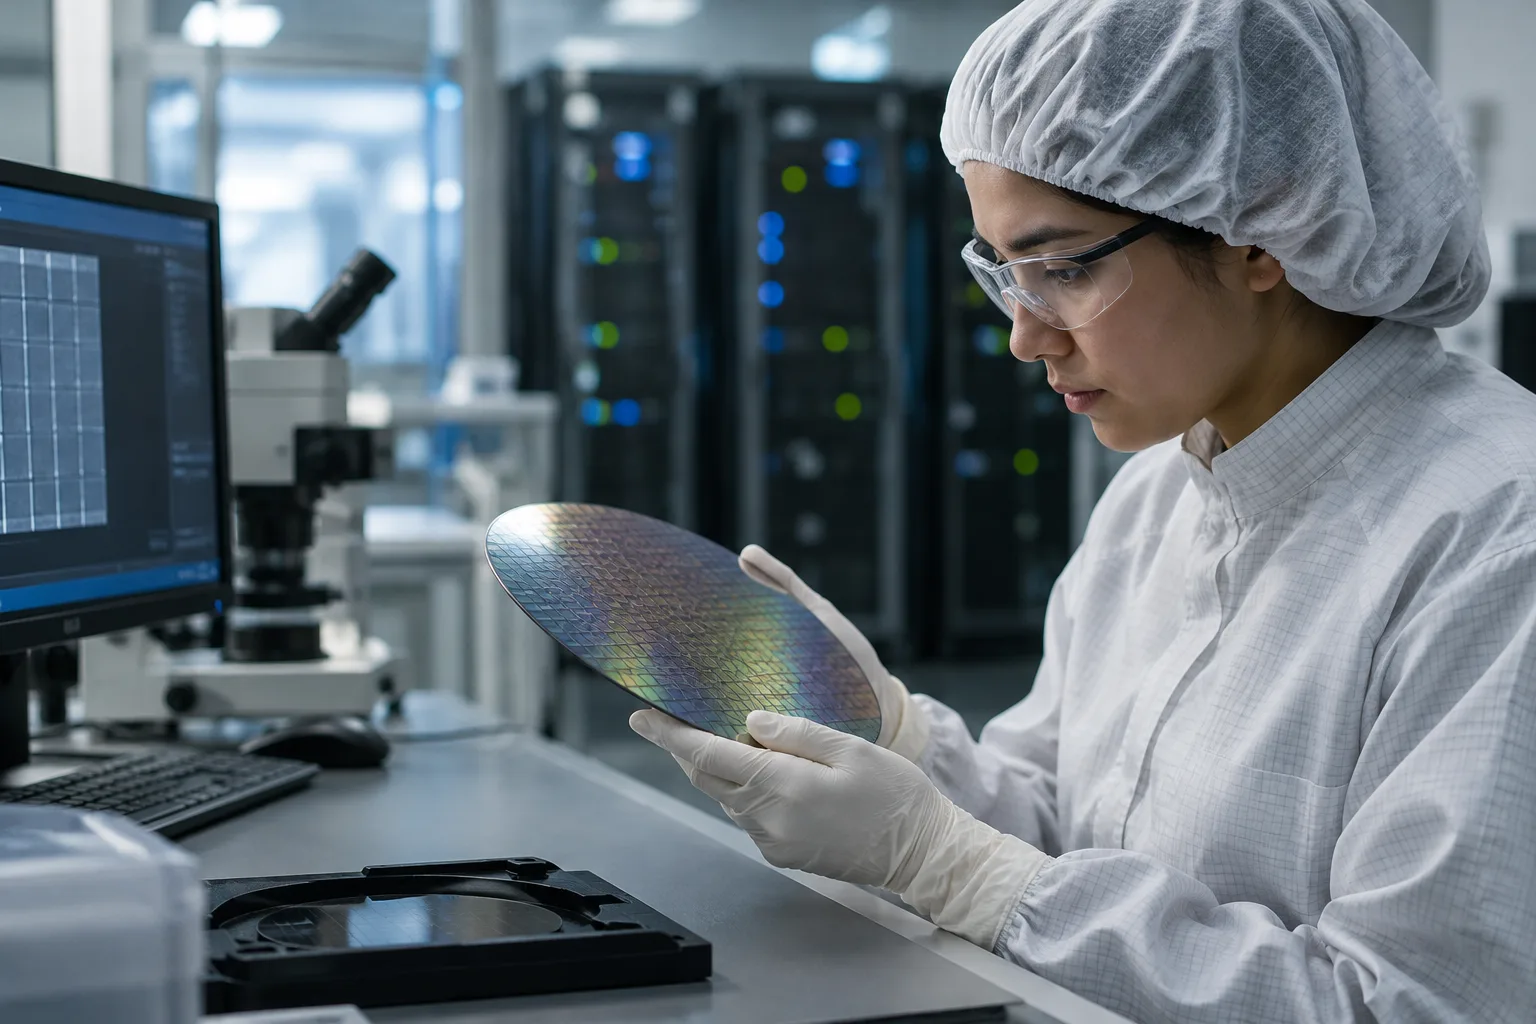

Britain’s attempt to keep more AI-hardware value at home just placed its biggest visible marker yet. On Nov. 11, GOV.UK said its Sovereign AI Venture Fund and the British Business Bank were backing Fractile, a London- and Bristol-based startup developing chips for AI inference, in a funding round worth more than £500 million and valuing the company at more than £5 billion. Reuters reported the same financing as a $720 million Series C at a $7 billion valuation, led by Thrive Capital, Founders Fund, Lightspeed and Redpoint.
That makes this more than another large venture round. It is a test of whether public money and private capital together can help turn a British AI-chip idea into a complete, shippable inference platform before larger incumbents close the same efficiency gap themselves.
The reader’s practical question is straightforward: can Fractile convert this financing into reliable hardware that cloud operators and model developers will actually deploy, or does the valuation mostly reflect strategic scarcity in a market hungry for alternatives to today’s accelerator leaders?
The most honest answer is that the round sharply improves Fractile’s odds, but it does not yet answer the commercial case. What it buys is time, talent, mask sets, software work, manufacturing relationships and customer trials. What it does not buy automatically is working silicon, acceptable yields, developer adoption or lower cost per useful task in production.
Why inference is the real battleground
Fractile is targeting AI inference, the stage at which a trained model serves answers to users. That matters because inference is becoming its own infrastructure problem. Training a frontier model is expensive and visible, but serving millions of prompts can become a bigger recurring cost center, especially when model weights and activations keep shuttling between compute and memory.
That data movement is the bottleneck Fractile is trying to attack. Technology coverage has described the company’s approach as bringing memory closer to the logic, including reported use of stacked DRAM, so the chip spends less time and energy making repeated round trips to external high-bandwidth memory. If that works at useful scale, the payoff is not abstract: lower latency, lower power draw and lower cost to deliver an answer.
That is the industrial logic behind the investment. Britain is not backing Fractile because the company has already shipped a market-proven chip; it is backing the chance that a domestic team can capture more of the jobs, intellectual property and downstream platform value in a part of AI infrastructure where demand is still expanding.
The market clearly finds that story compelling. Fractile, founded in 2022 and led by AI researcher Walter Goodwin, reportedly raised roughly $220 million earlier in 2026. A move from that round to a more-than-£5 billion valuation now is a strong signal that investors expect inference demand to keep rising and believe there is room for a credible challenger. It is not a reading on revenue, installed base or shipped products.
The five gates between a design and a business
For buyers and policymakers, the right scorecard is not the valuation. It is five gates.
First comes tape-out and working silicon. Public sources reviewed for this story do not disclose a tape-out date, fabrication partner, process node or silicon test results. Until chips come back from the fab and perform as intended, every architecture pitch remains partly theoretical.
Second is performance and energy on production-style workloads. Fractile has been associated with claims of up to 100-times better performance and 90% lower energy use, but those are company or investor-facing claims, not independently audited production benchmarks. The relevant question is not whether a narrow demo looks impressive; it is whether representative models show better throughput, latency and power consumption at the system level.
Third is software compatibility. AI buyers rarely purchase a chip in isolation. They buy a toolchain, compiler, runtime and operator support that fits the models they already use. A promising design can still lose if developers have to rewrite too much code, accept model limitations or live with immature tooling.
Fourth is customer qualification. Reuters reported that Fractile plans to launch its first commercial chip in 2027. That is an important milestone, but “commercial” is not the same as “qualified at scale.” Cloud providers and enterprise operators need reliability testing, deployment support and evidence that the hardware behaves predictably under real traffic.
Fifth is cost per reliable task at useful volume. Even a technically elegant accelerator can stumble on packaging bottlenecks, low yields or expensive memory arrangements. The public record does not say how much of this round is reserved for engineering, mask sets, packaging, software or deployment, and it does not establish expected chip volume or unit economics.
What public backing changes — and what it doesn’t
The government’s participation matters even without disclosing the size of its stake or any governance rights. It signals that Britain is willing to use public capital to gain exposure to domestic AI capability rather than watching the highest-value layers consolidate abroad. For workers and founders in the U.K. tech ecosystem, that can help with recruitment, confidence and ecosystem formation. For suppliers and prospective partners, it may make Fractile look more durable.
It also has strategic value for customers who may never switch entirely away from incumbent GPUs. A credible second source in inference hardware can improve bargaining power, diversify supply and pressure larger vendors to improve inference economics faster.
Still, state backing should not be confused with state certification. The announcement is not a purchase order, and it is not proof that Fractile has solved manufacturability, software maturity or customer adoption. Nor should the roughly $7 billion valuation be read as proof of product-market fit. It reflects the price sophisticated investors are willing to pay for a scarce option on future silicon in a market where incumbents such as Nvidia and AMD, along with Google, Amazon, Cerebras and others, have deeper manufacturing and software resources.
That is why this financing matters beyond Fractile itself. If the company clears the next two years of technical and commercial gates, Britain will have shown that public capital can help fund not just AI research, but a domestic hardware platform with spillover benefits in talent, supply chains and leverage. If it does not, the round will look more like a very expensive placeholder for a capability the country still does not control.
For now, the most useful way to read the news is neither as a breakthrough nor as hype. It is as a well-funded attempt to buy enough time to prove that a memory-centered inference design can survive contact with fabs, software stacks and customer procurement. The first commercial chip planned for 2027 is the starting gun for that test, not the finish line.
 By
 By




 By