
Lam Research reported a record quarter for the period ended Sept. 27, 2026, posting $8.219 billion in revenue, up 22% sequentially and 54% from a year earlier, as chipmakers continued spending on the equipment needed to expand semiconductor manufacturing capacity. Gross margin reached 52.3%, operating margin 40.0%, and net income $2.75 billion, according to the company’s earnings release.
That is a strong semiconductor and infrastructure signal because Lam sits upstream of the AI-server buildout. Before more accelerators can ship, more wafers have to move through more process steps on more tools. But the key question after this report is no longer whether AI-related chip spending is real. Lam’s numbers say it is. The harder question is whether that spending is turning into durable, usable capacity—or whether the industry is moving into a phase where tool supply, fab readiness, installation, qualification and eventual utilization matter more than another headline revenue beat.
What Lam’s quarter does, and does not, prove
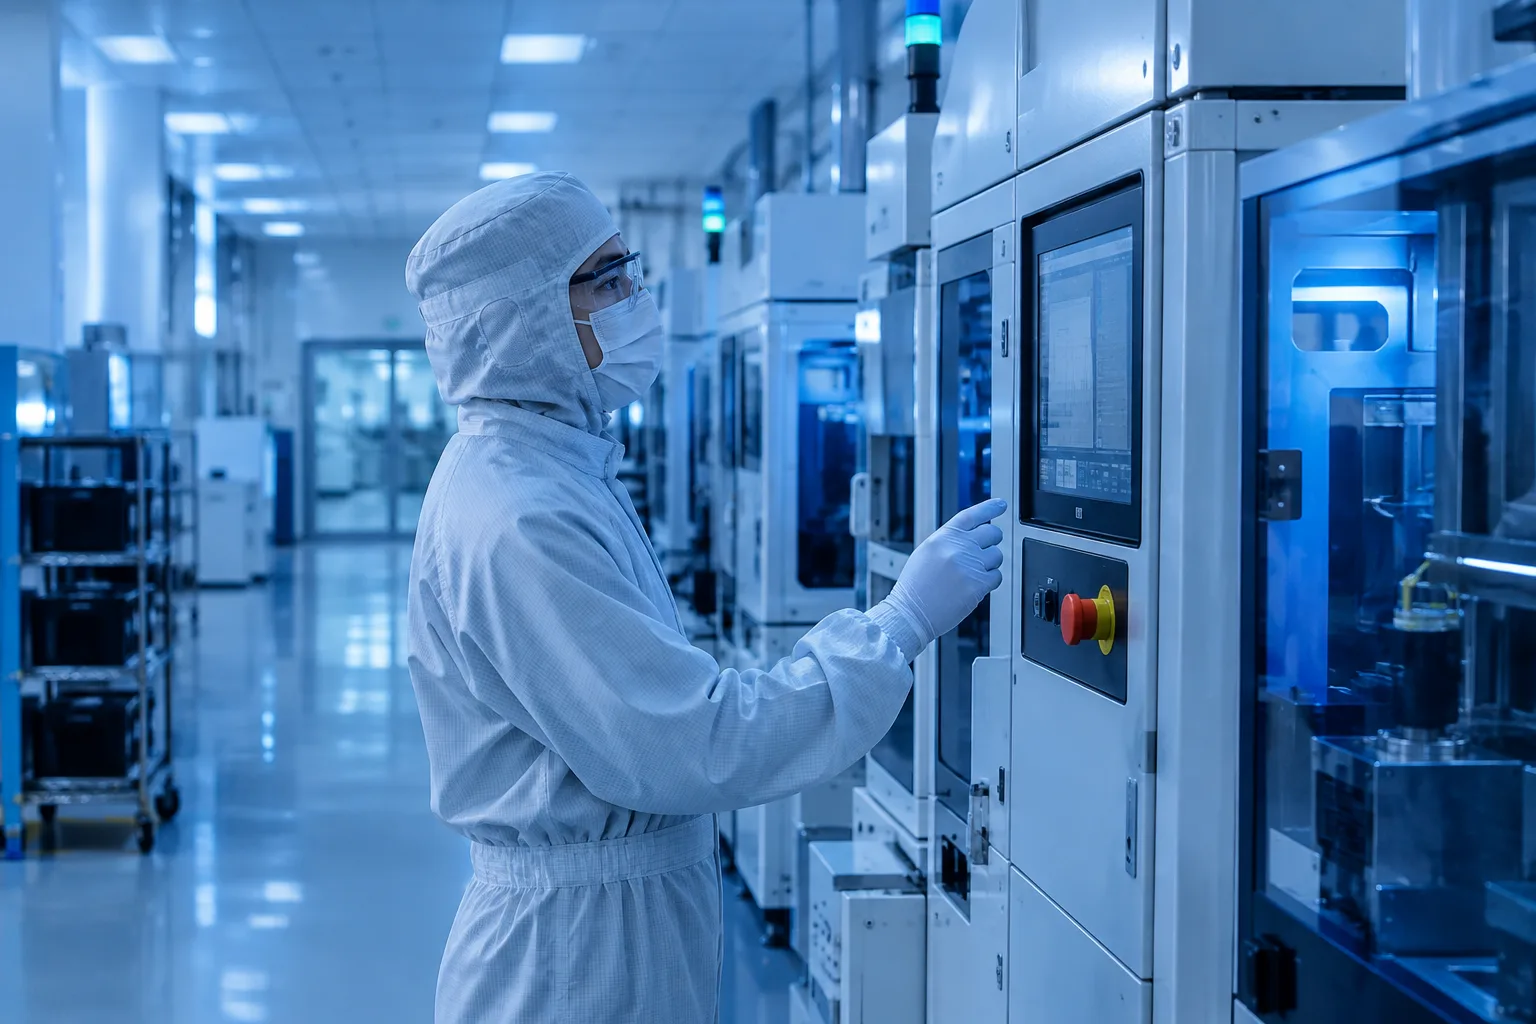
Lam sells wafer-fabrication equipment used in deposition, etch and related semiconductor processes, along with customer-support services. Its customers span memory, logic and advanced packaging, which is why a quarter like this should be read as a supply-chain sensor, not as a one-line verdict on “AI demand.”
Within the reported revenue, about $5.73 billion came from systems and about $2.49 billion from customer-support-related revenue and other. That mix matters. Systems revenue points to customers still buying the tools required to add or upgrade manufacturing capacity. The support business shows Lam is also monetizing a large installed base already operating in fabs, which can make results more resilient than a pure new-tool story.
Profitability was also unusually strong. A 52.3% gross margin and 40.0% operating margin tell readers this was not merely a volume quarter. Lam converted demand into earnings efficiently, even as semiconductor equipment remains exposed to complex supply chains, export rules and customer project timing. The company said AI is increasing semiconductor demand and device complexity, while investments in technology inflections and manufacturing capacity are supporting growth.
What the quarter does not prove is just as important. Lam does not disclose a full AI-versus-non-AI revenue split, a complete backlog picture, or how much demand is tied specifically to memory, foundry-logic, advanced packaging or mature-node applications. So this report confirms strong spending on semiconductor capacity in the reported period; it does not show that every segment is equally healthy or that all of the resulting capacity will be profitably used.
Why the December guide drew more scrutiny than the September results
Lam guided to about $8.6 billion in revenue, plus or minus $400 million, for the December 2026 quarter, with adjusted diluted EPS of $2.33, plus or minus $0.15. At the midpoint, that is still growth from a record base. Yet it was not the kind of clear upside surprise some investors had come to expect, and market coverage from Investopedia said the shares fell sharply the next day as those expectations reset.
That reaction says less about whether Lam had a strong quarter than about where the market now sees the constraint. Earlier in an upcycle, the central debate is demand: are customers willing to spend? Lam’s September numbers answer yes. Later, the debate shifts to conversion: how quickly can demand become shipped tools, installed tools, qualified tools and productive wafer output?
That chain is where semiconductor-equipment results become more nuanced than AI-server headlines. Lam can influence tool design, manufacturing, service and some aspects of delivery. But other links in the chain sit outside its direct control. Suppliers determine whether critical components arrive on time. Fab customers determine site readiness, power, cleanroom completion, labor, installation schedules and qualification pace. Export controls and regional policy can alter what can be shipped where and when. Customer technology transitions can also change the mix of tools needed, even when total spending remains elevated.
This is why a record quarter and a merely solid guide can coexist. Demand can be strong enough to fill the pipeline while the pace of realizing that demand into usable capacity becomes less predictable. For device makers, server planners and component buyers, that distinction matters more than a simple up-or-down reading on semiconductor capex.
The practical test for AI-capacity durability
For Devices readers, the most useful takeaway is to separate several signals that are often collapsed into one. Equipment revenue shows customers are spending. It does not show that all tools are already installed, that those tools are fully qualified, or that the resulting wafers will feed products earning attractive returns. In an AI market, those are materially different stages.
The next test is whether later data show the bottleneck easing or simply moving around. Investors and procurement teams should watch for evidence on lead times, shipment timing, customer capex follow-through, memory-versus-logic mix, geographic exposure and the durability of margins. Later commentary on bookings, backlog trends, fab ramps and utilization will matter because they help distinguish a healthy capacity buildout from a quarter shaped by timing, mix or backlog conversion.
Lam’s report is therefore best read as confirmation that upstream semiconductor demand remains powerful, not as proof that the AI buildout has become frictionless. The company’s own risk framing still includes customer timing, fab construction schedules, export controls, supply constraints, customer mix and shifts in semiconductor demand. Those are not side notes now; they are the variables most likely to determine whether today’s spending becomes tomorrow’s dependable capacity.
In practical terms, Lam has given the market evidence that customers are still funding the manufacturing layer beneath AI infrastructure. What it has not yet given—because quarterly equipment results cannot give it—is a clean read on how much of that spending will translate, on schedule and at attractive economics, into qualified chips powering revenue-generating compute. That is why the quarter looked excellent, and why the guide still left room for doubt.
 By
 By
 By
 By