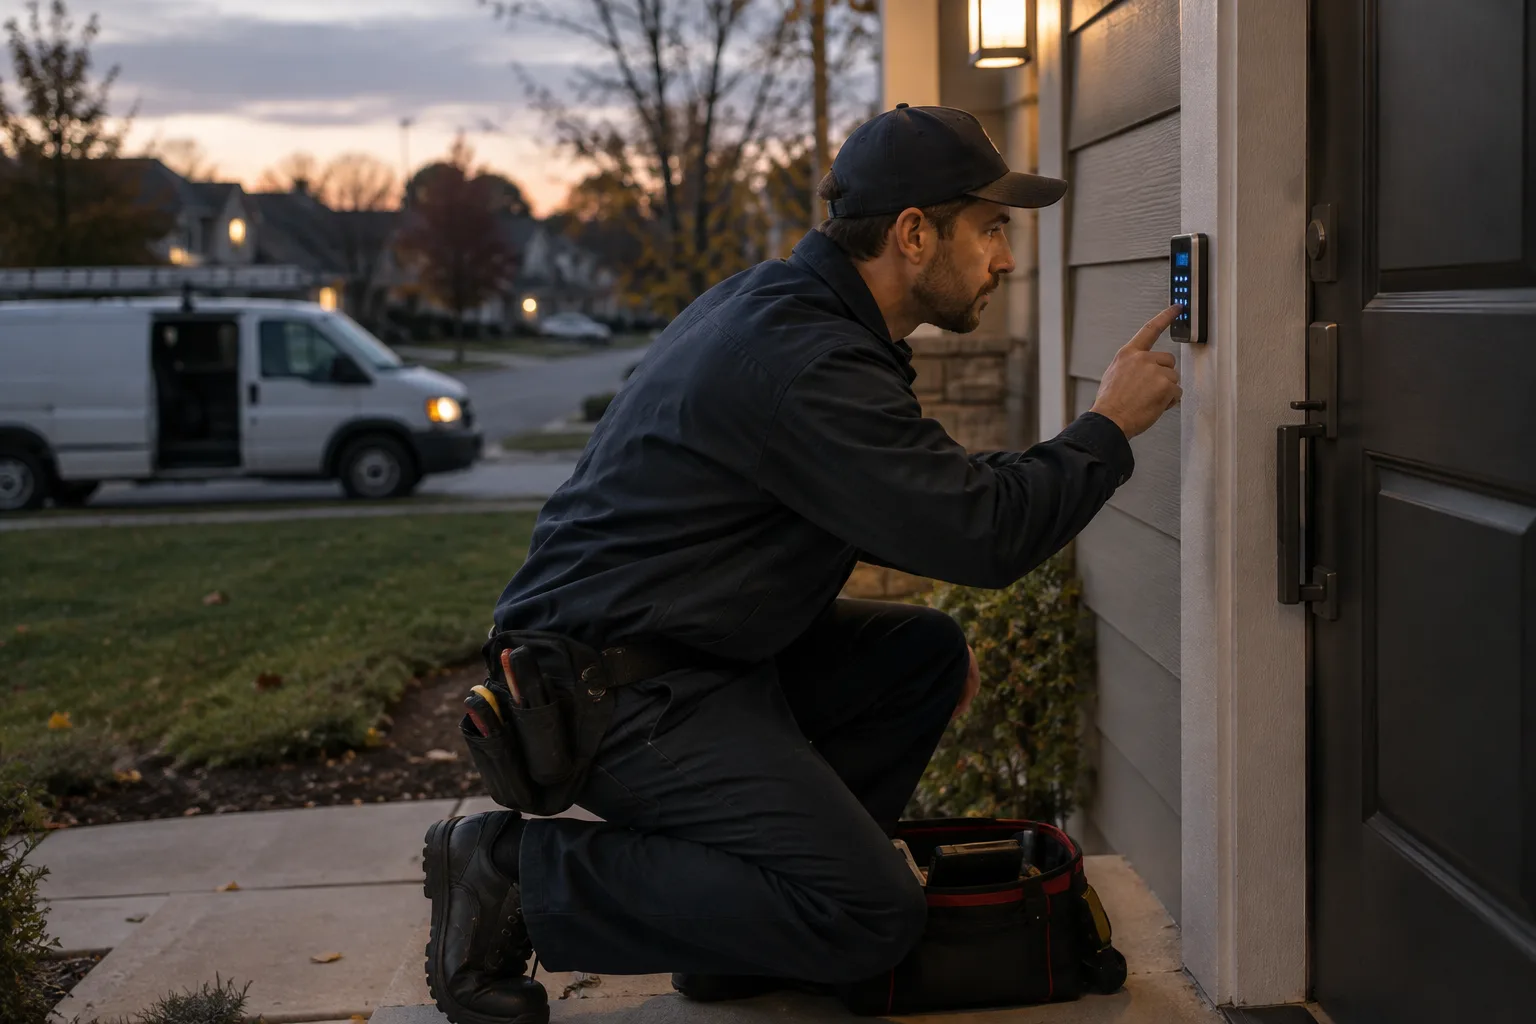

ADT has agreed to be acquired by Thrive Holdings in an all-cash transaction that values the home and small-business security company at roughly $7.6 billion in equity value and $15.3 billion in enterprise value. Under the proposed deal, ADT stockholders would receive $10.00 per share, a 45.6% premium to the company’s unaffected Oct. 27 closing price and a 52.1% premium to its 30-day volume-weighted average through that date. The immediate significance is not just another take-private. It is a bet that a technology-minded, long-term owner can improve a service people depend on when something goes wrong in the real world.
That is the real question for customers, employees, vendors, insurers, and investors: can Thrive use capital and engineering to make ADT’s security service more accurate and responsive, or will the transaction mainly turn a trusted service network into a platform for cost optimization and deeper data extraction?
What Thrive is actually buying
The ADT announcement makes clear that this is not a simple hardware or software story. ADT sells a recurring service built on installed equipment, monitoring operations, professional installation and repair, customer support, and long-running customer relationships. The company says its nationwide network serves millions of homes and employs more than 12,000 people. That physical footprint is the asset.
Thrive, for its part, is offering a different ownership model from a standard short-hold private-equity play. ADT says Thrive operates with permanent capital and already owns more than 75 businesses across accounting, IT services, and the built environment. In ADT, Thrive would get a brand, technicians, monitoring centers, installed devices, and the right to invest in a system that already reaches into customers’ homes and small businesses.
The deal is definitive but not done. ADT’s board approved it unanimously, and the companies expect to close in the first quarter of 2027, subject to stockholder approval, U.S. antitrust clearance, and other customary conditions. The agreement has no financing condition, and financing commitments come from funds managed by Apollo Global Management affiliates. But ADT can still solicit competing proposals during a 30-day go-shop period ending Nov. 28, with a possible 10-day extension for qualifying bids. Until closing, ADT remains independent; if the transaction closes, it will become privately held and leave the New York Stock Exchange.
Where technology could create value — or risk
The strategic logic rests on a practical service chain. A sensor, camera, or alarm triggers an event. That event flows to ADT’s systems and monitoring operation. A human professional decides what it means, whether to contact the customer, whether to escalate, and what information to pass along. In other cases, the issue is not an intrusion at all but a device fault, a weak connection, a battery problem, or a service need that requires a technician or support agent.
That is where Thrive sees room for engineering. ADT and Thrive describe possible gains in reducing false alarms, making notifications more informative, identifying equipment problems earlier, improving the information available to monitoring professionals, and making service more effective. Those are sensible pressure points in a mature security business. Filtering duplicate or low-value alerts could reduce nuisance events. Better telemetry could catch failing equipment before it causes a missed signal. Richer device context could help monitoring staff decide faster and with less guesswork. Smarter dispatch and service tools could lower repeat truck rolls and improve the customer experience.
But none of that is the same as a shipped product or a proven operating result. The companies did not announce a specific AI system, launch schedule, customer metric, or productivity target. They did not publish a baseline for false alarms, response times, churn, equipment failures, or service costs. In a business tied to emergency-adjacent decisions, that matters. A model that misclassifies an event, downgrades a real threat, floods a customer with bad alerts, or changes queue priority in the wrong way can create safety problems as easily as it creates savings.
That is why governance matters as much as code. The useful controls here are mundane but consequential: human review on consequential decisions, confidence thresholds for automated recommendations, audit logs, reversible rollouts, tested fallback procedures when systems fail, and data minimization. ADT says its privacy and data-protection policies will remain unchanged until closing and that no new data sharing will occur without customer permission. What remains unanswered is the harder part: which data sources would power any future improvements, how long that information would be retained, whether models would be trained on customer data, and how customers could opt out without losing core monitoring service.
The business test for customers, workers, and investors
For customers and small businesses, the practical takeaway is to watch the service contract and operating model, not the branding around innovation. Does human-supervised monitoring remain central? Do service levels change? Is any new data collected, shared, exported, or deleted differently? How will false alarms and missed alarms be measured and reported? If a technology change contributes to a service failure, who is accountable and what remedy exists?
For employees, especially monitoring staff and field technicians, the unresolved issue is whether new tools are built to augment work or to compress it. The companies say they plan continued investment in people and products, but there is no public operating plan yet for staffing, compensation, training, dispatch logic, performance measurement, or how much decision-making could shift from workers to software. In a field-service business, technology can remove drudgery; it can also shift risk and workload onto fewer people.
For investors and policymakers, the transaction is also a test of a broader pattern: technology-oriented owners buying operationally intensive businesses for distribution, workflows, domain data, and recurring customer relationships. ADT is attractive precisely because it is hard to replicate. But the premium Thrive is paying buys control, not proof. The announcement does not disclose post-close leverage, interest burden, financing covenants, or return thresholds for the technology plan. Private ownership may also mean less routine public disclosure once the deal closes.
The SEC filing lists the familiar risks that could still derail or reshape the transaction: stockholder rejection, antitrust conditions, competing bids, litigation, employee retention, supplier and customer disruption, and management distraction. Even if the deal closes on time, the technology case will remain a thesis until ADT and Thrive show measurable improvements in reliability, nuisance alerts, equipment health, and service quality without expanding surveillance or weakening human accountability.
That is the standard worth applying to this deal. If Thrive can make ADT’s system more accurate, more informative, and easier to service while keeping customers in control and humans accountable, it will have proved something meaningful about technology-led ownership in a trust-sensitive industry. If the result is opaque data expansion, brittle automation, or cost cuts marketed as innovation, the transaction will have exposed the limits of applying a software playbook to a business people call when they need help, not just convenience.
 By
 By
 By

 By

 By